National Market Outlook - September 2026
Monthly Economic Summary
SEPTEMBER 2026
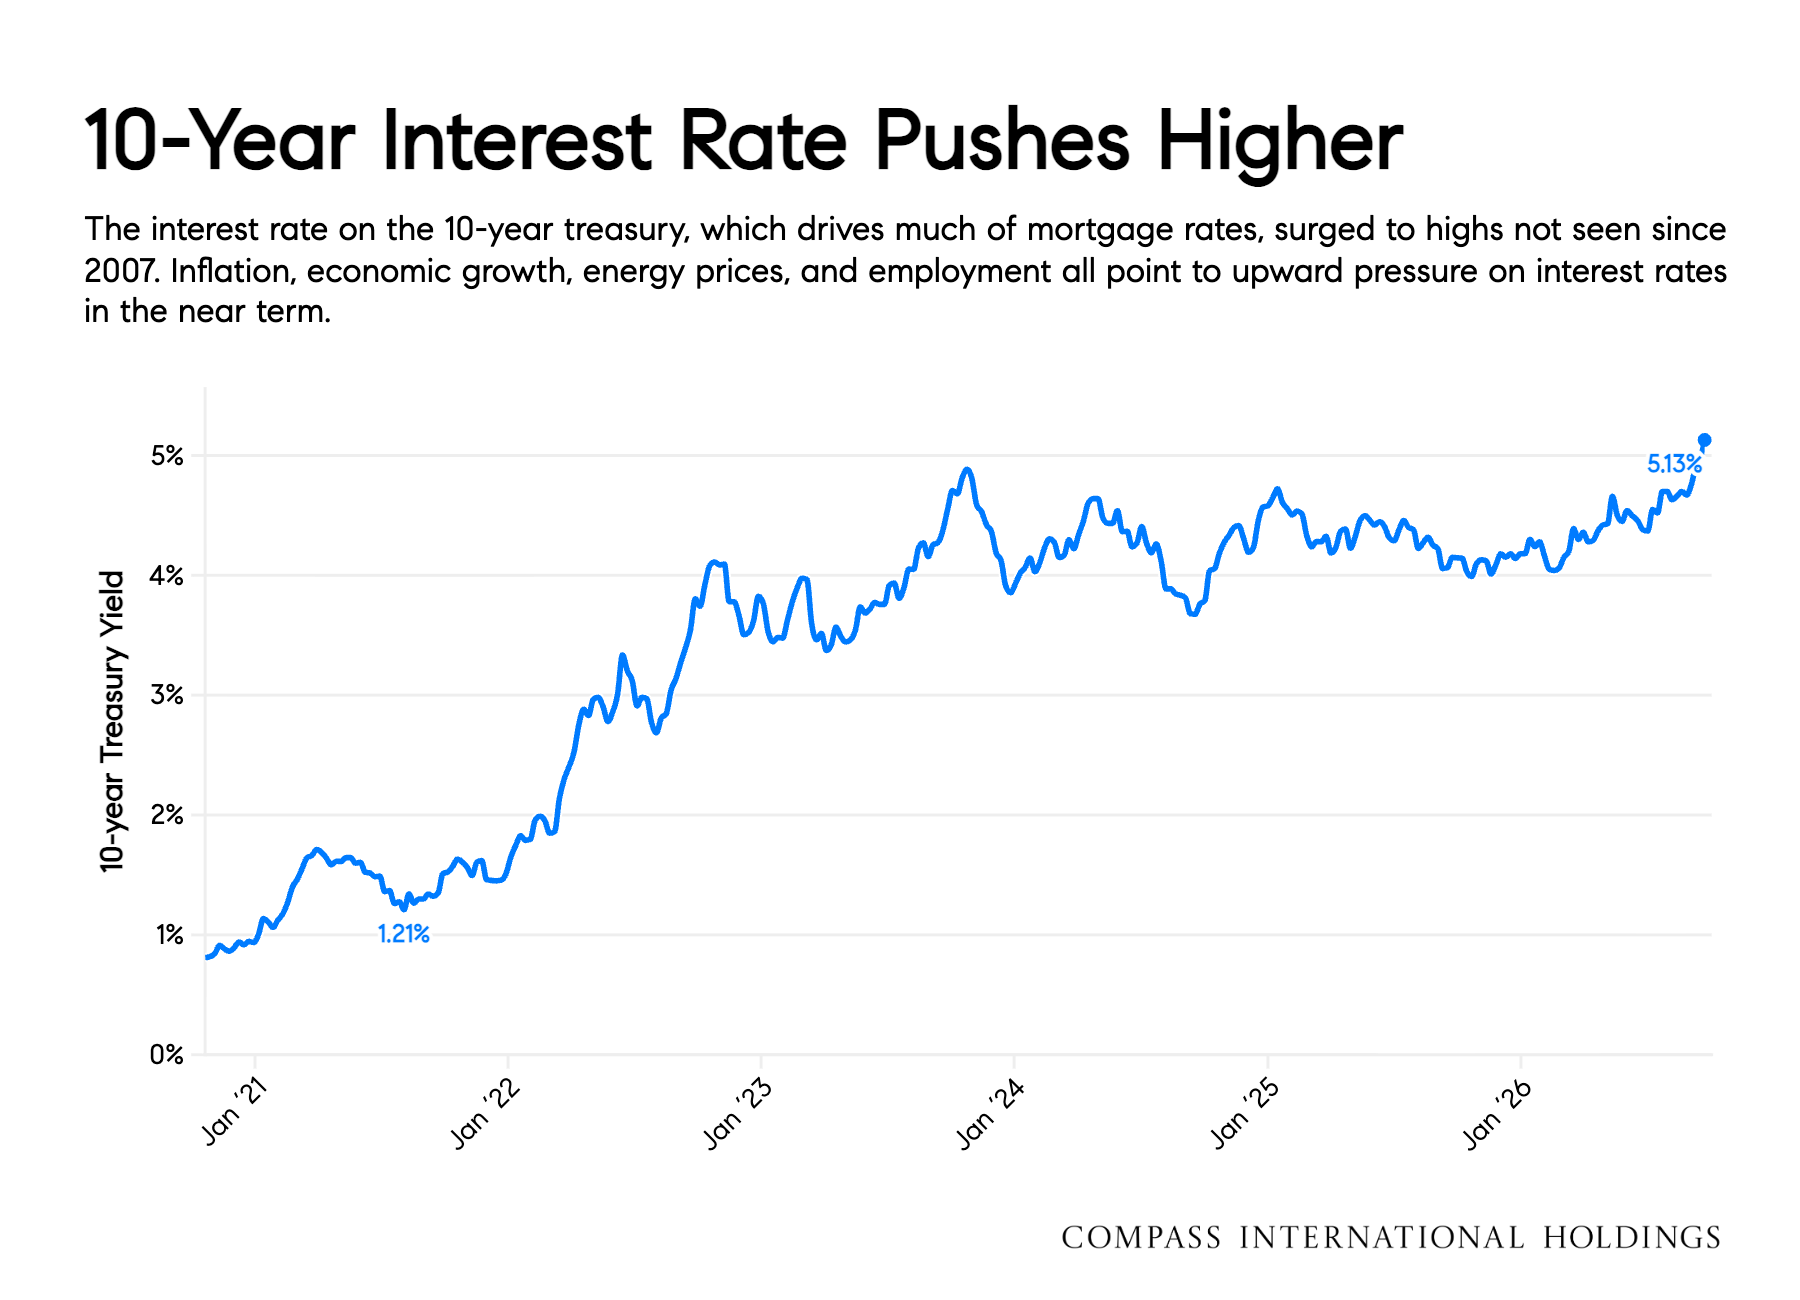
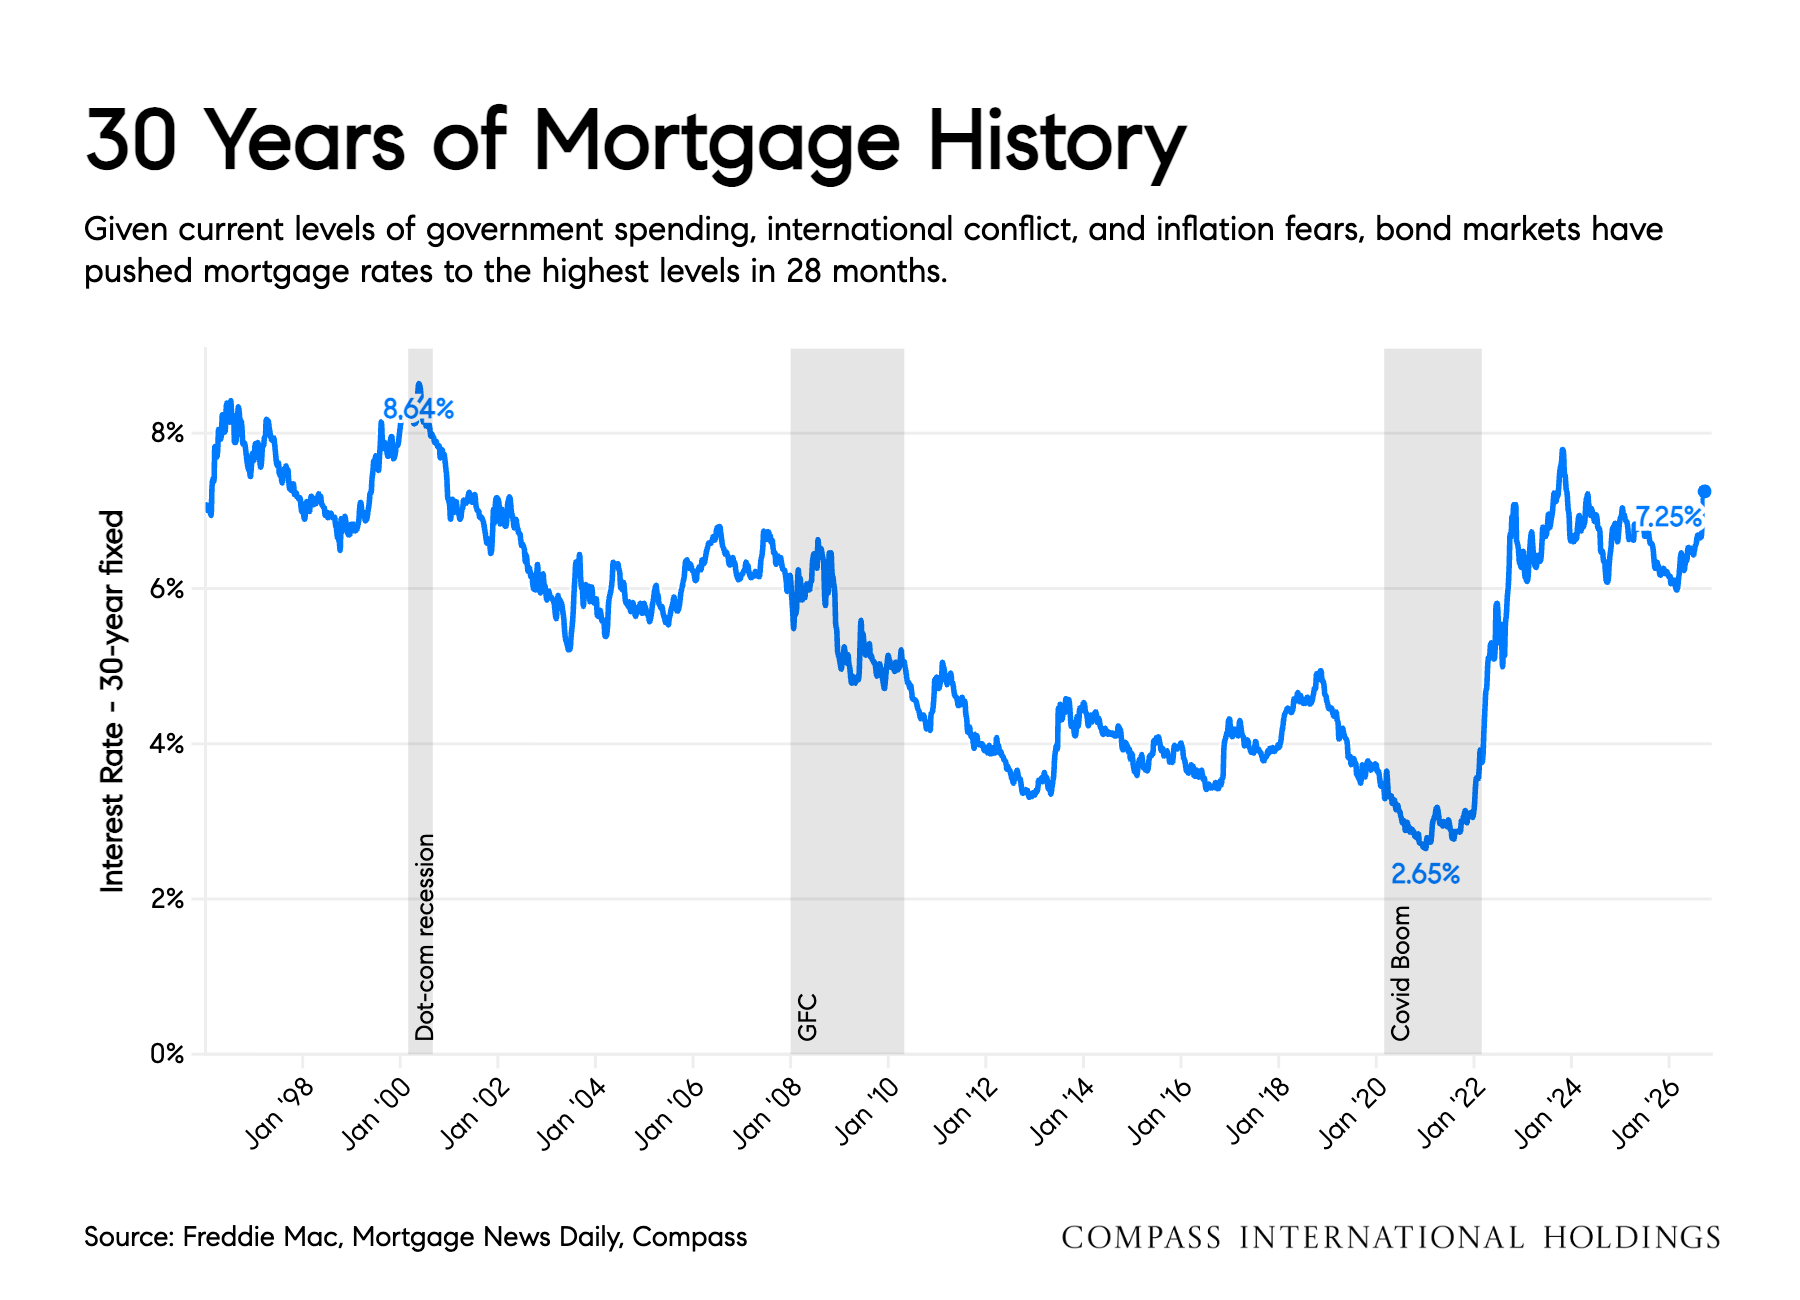
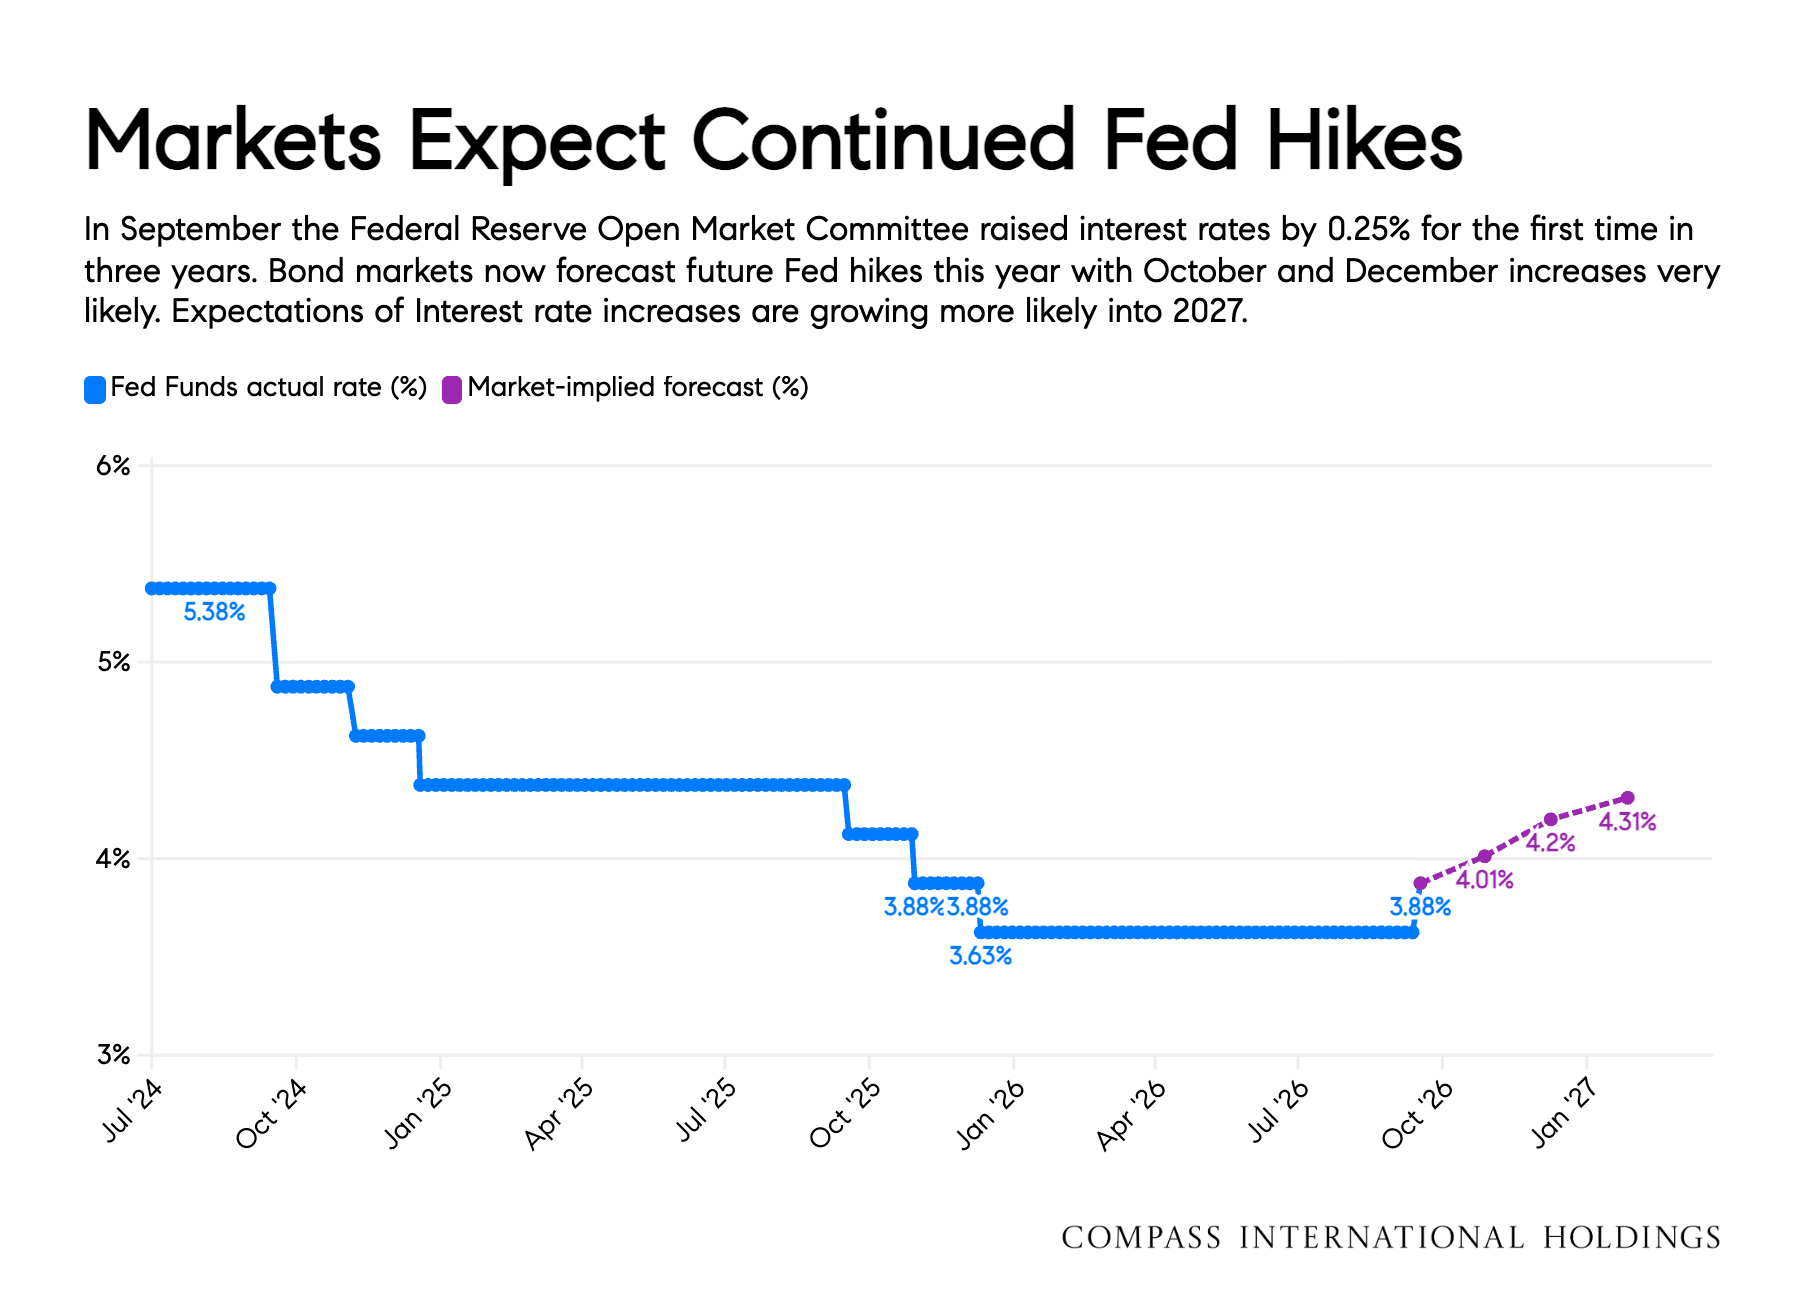
September brought the sharpest shift in the housing market we've seen this year, and it started in the bond market. The 10-year Treasury yield pushed above 5.1%, its highest level since 2007. Mortgage rates followed to about 7.25%, the highest in 28 months. The Fed raised rates for the first time in three years, and bond markets now expect more hikes in October and December.
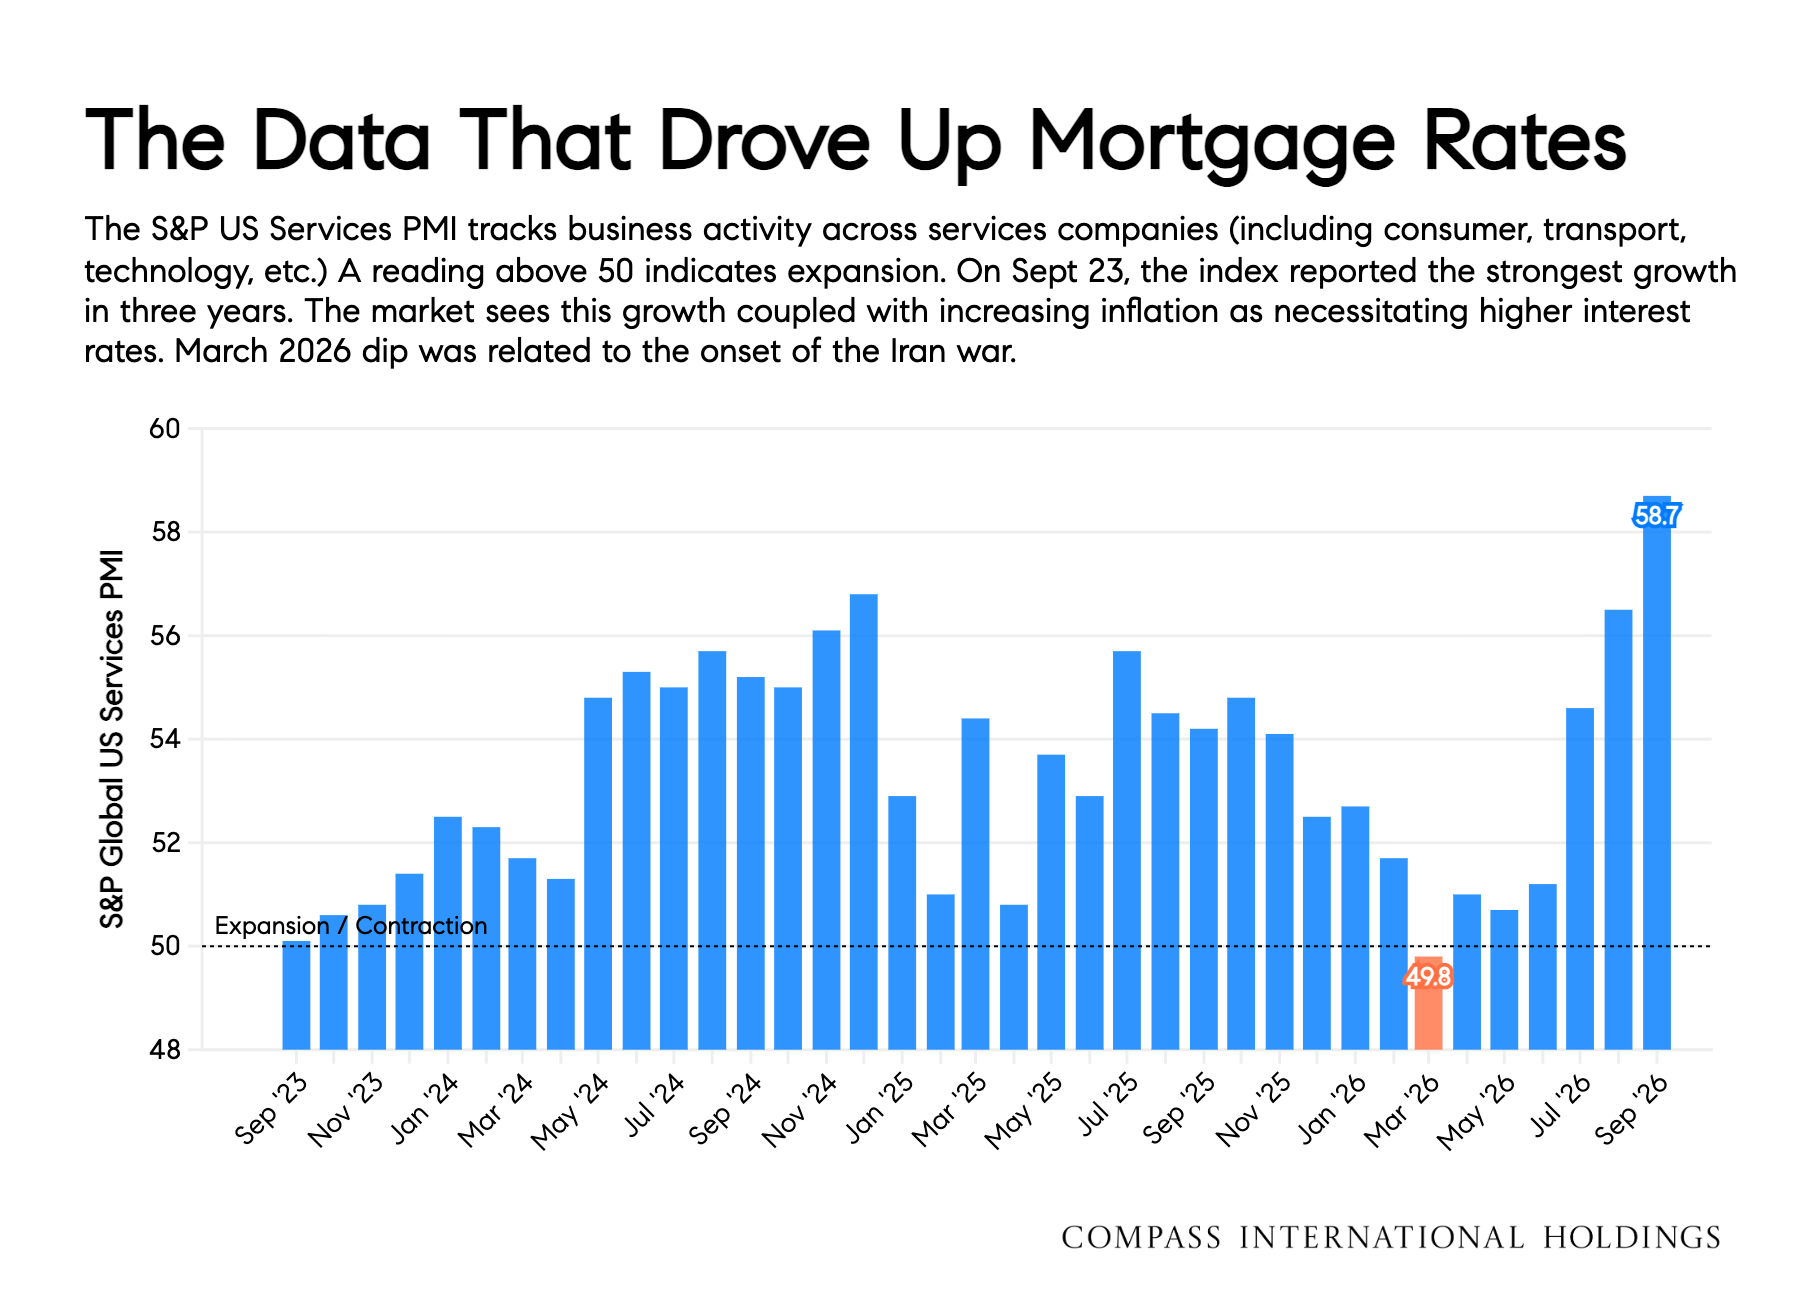
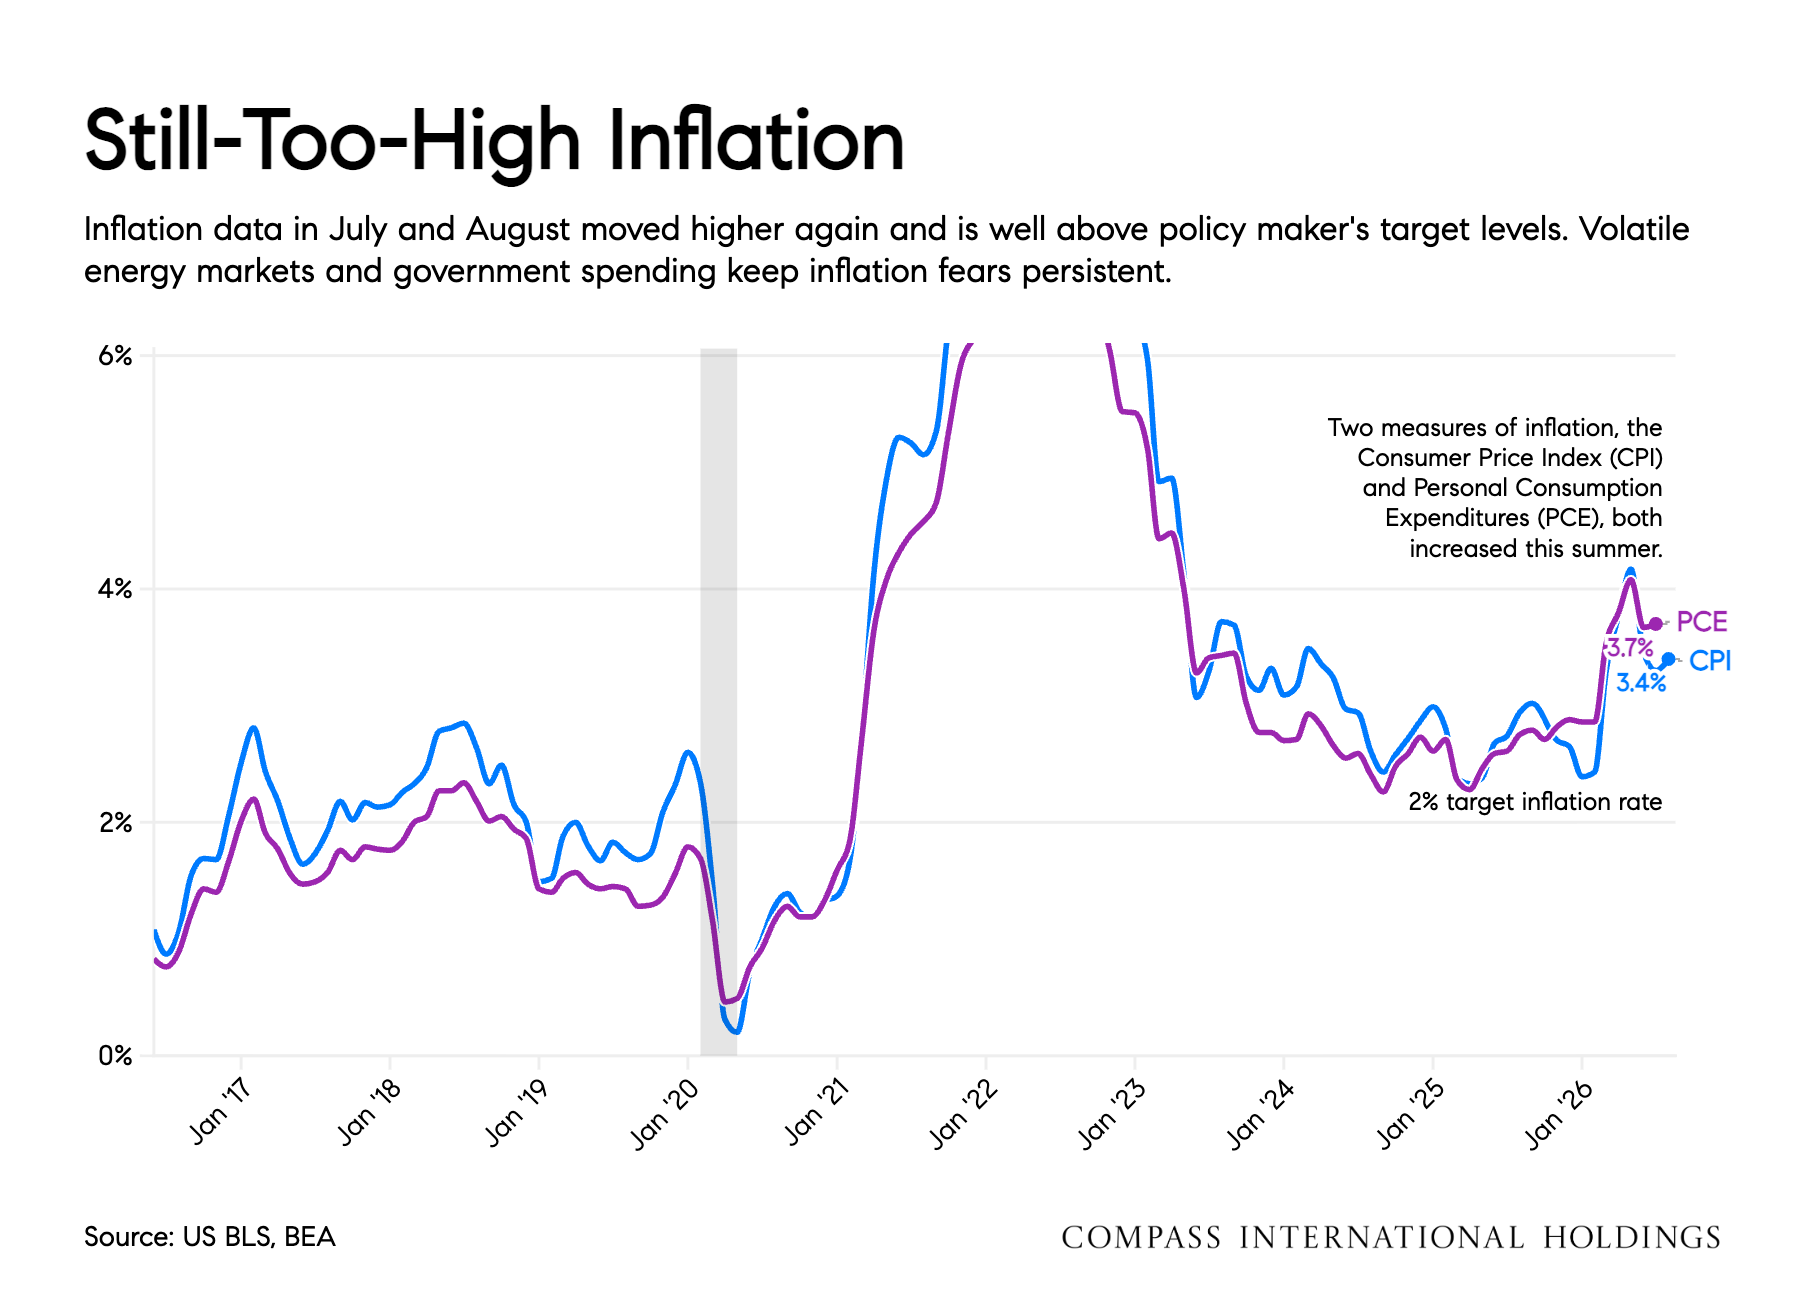
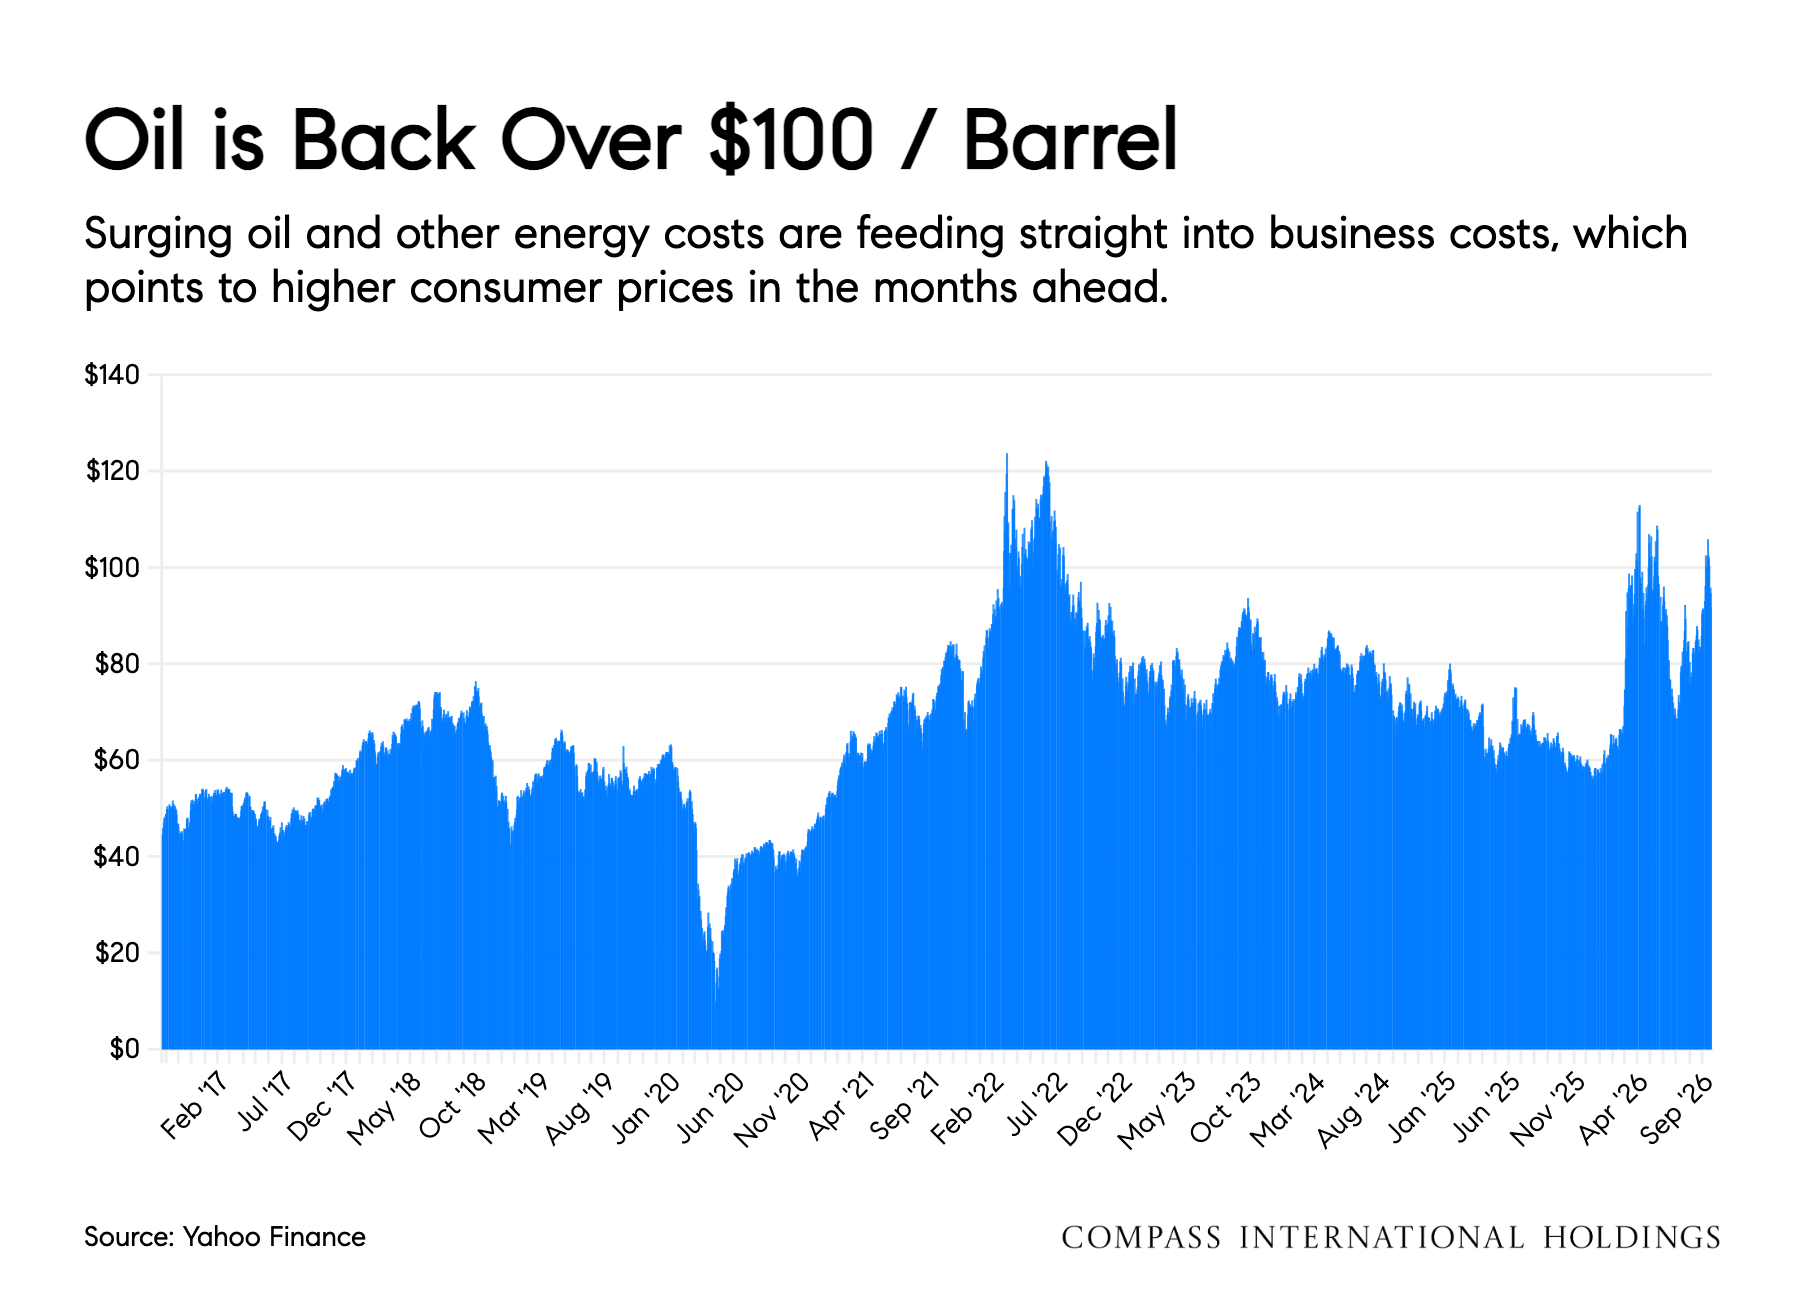
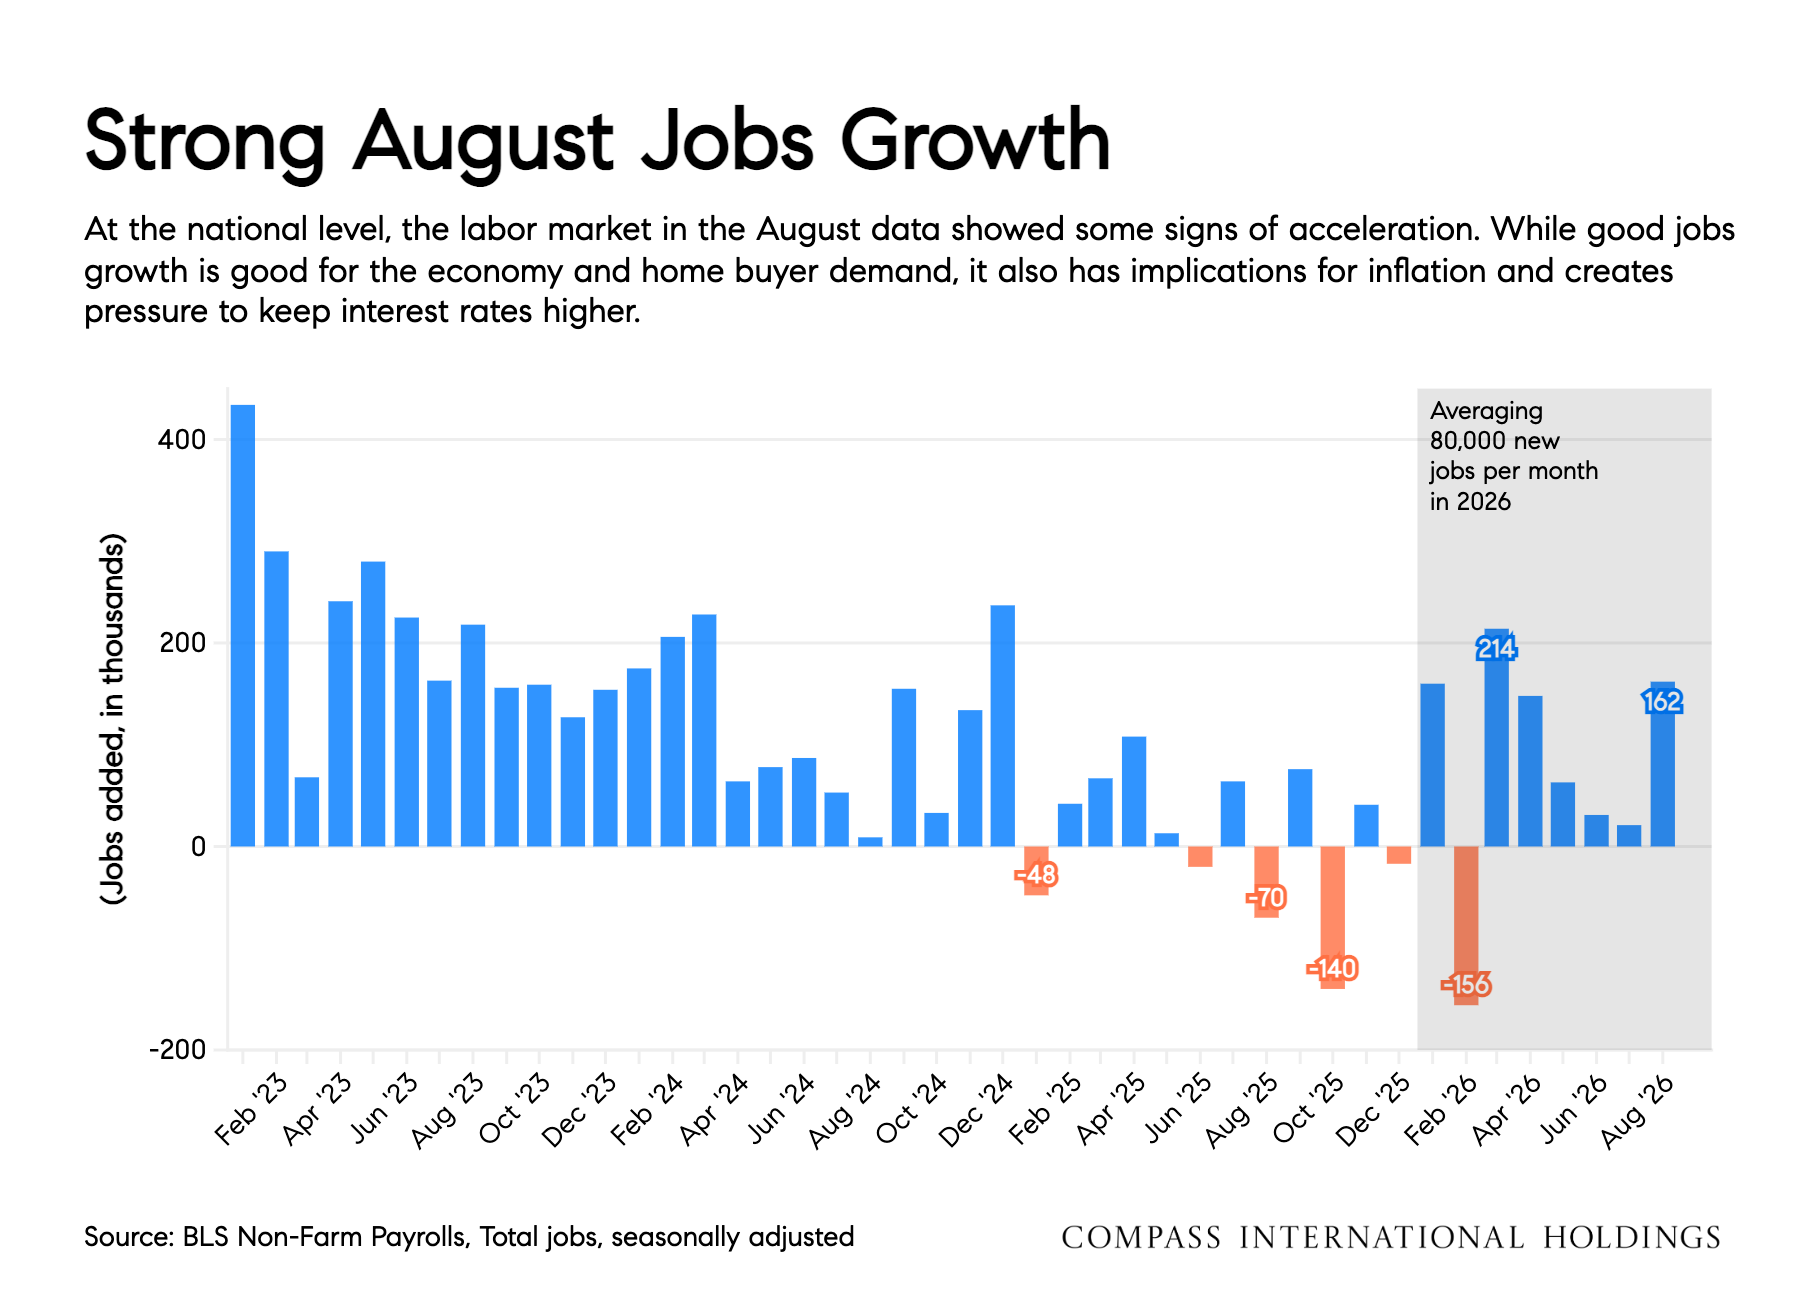
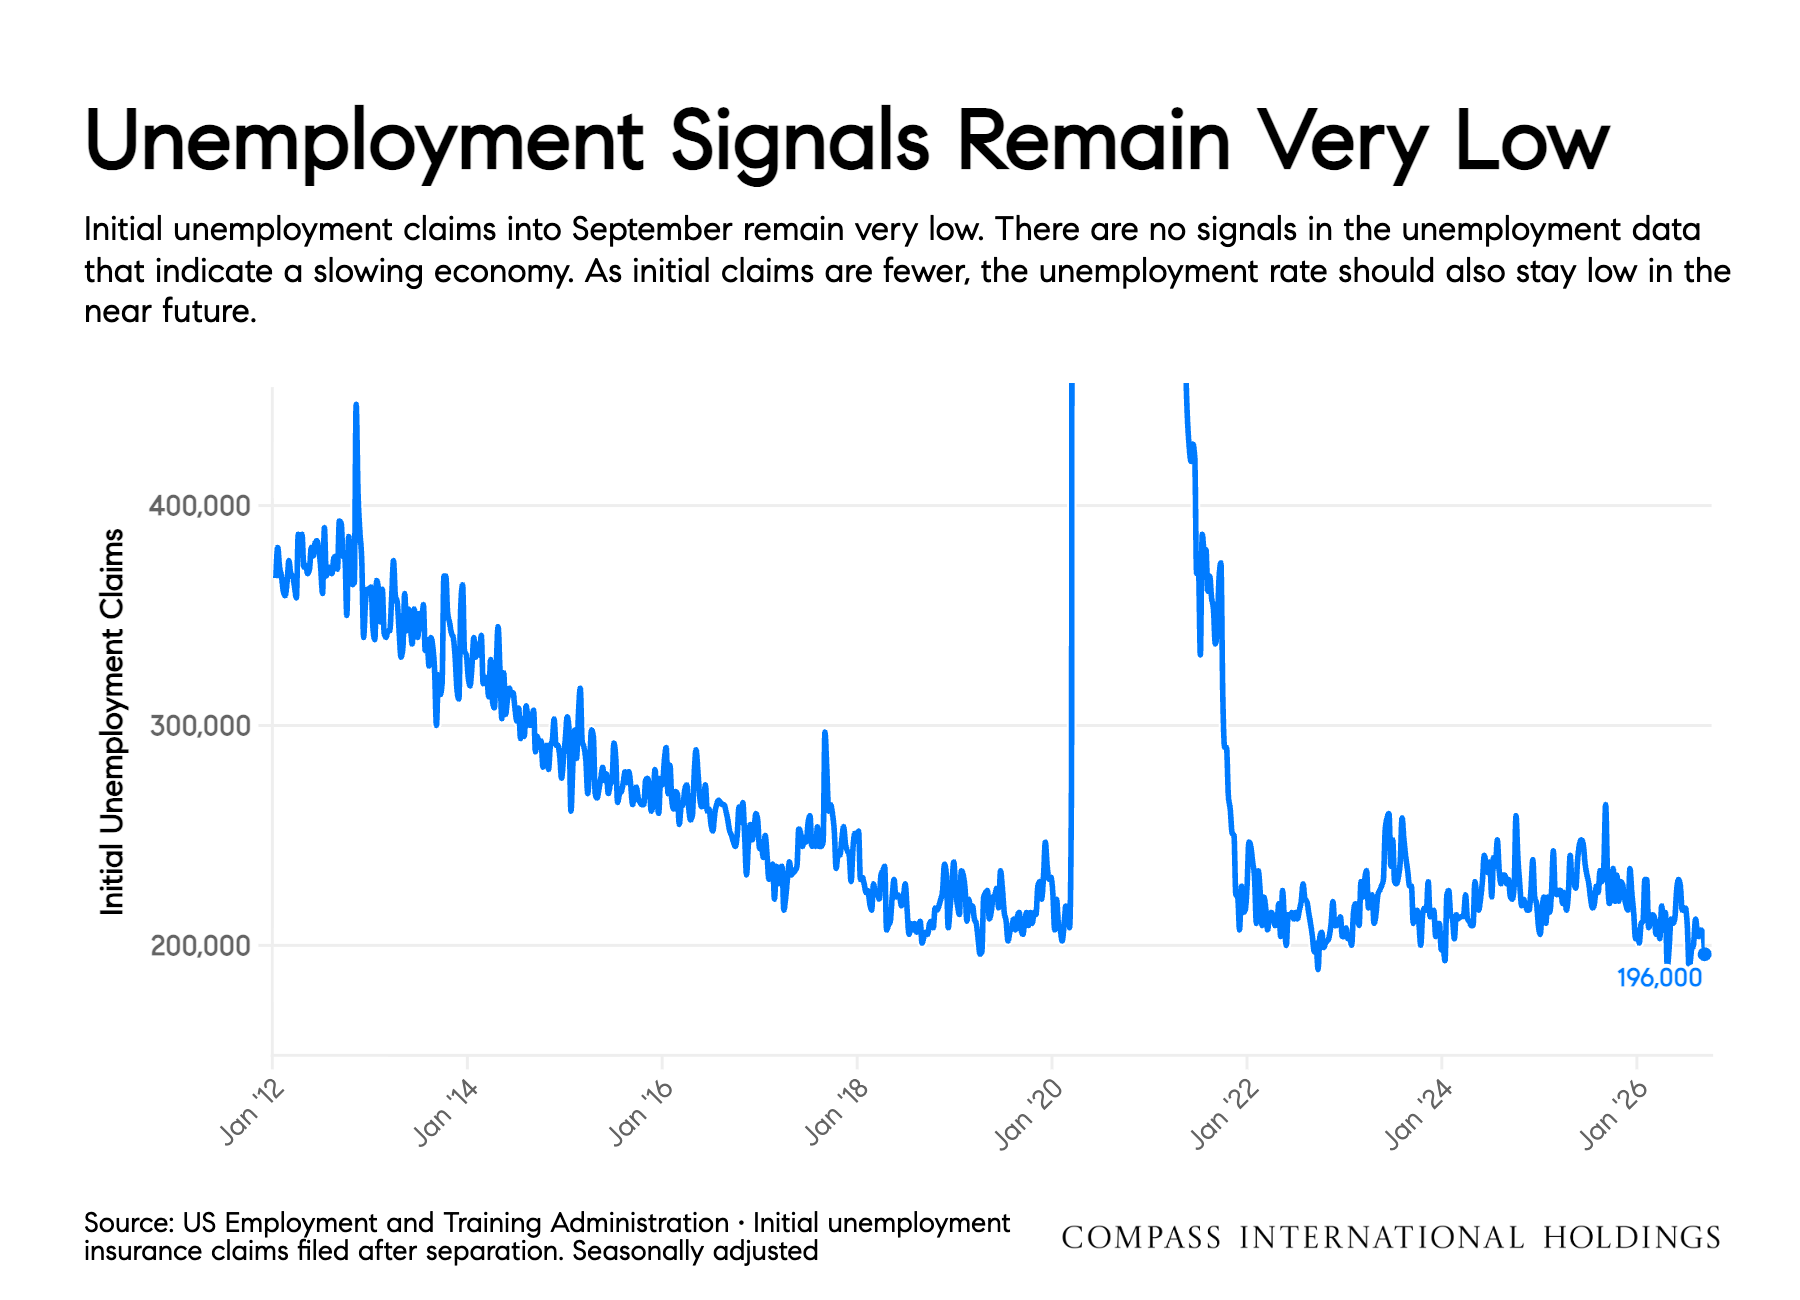
The economy is running hot. Services activity just posted its strongest reading in three years. August added 162,000 jobs, unemployment claims remain near historic lows, and oil is back above $100 a barrel. Inflation moved up again this summer, with CPI at 3.4% and PCE at 3.7%, well above the Fed's 2% target. Markets have moved from stagflation fears to 'growthflation.”Stronger growth plus rising prices clearly calls for higher rates.
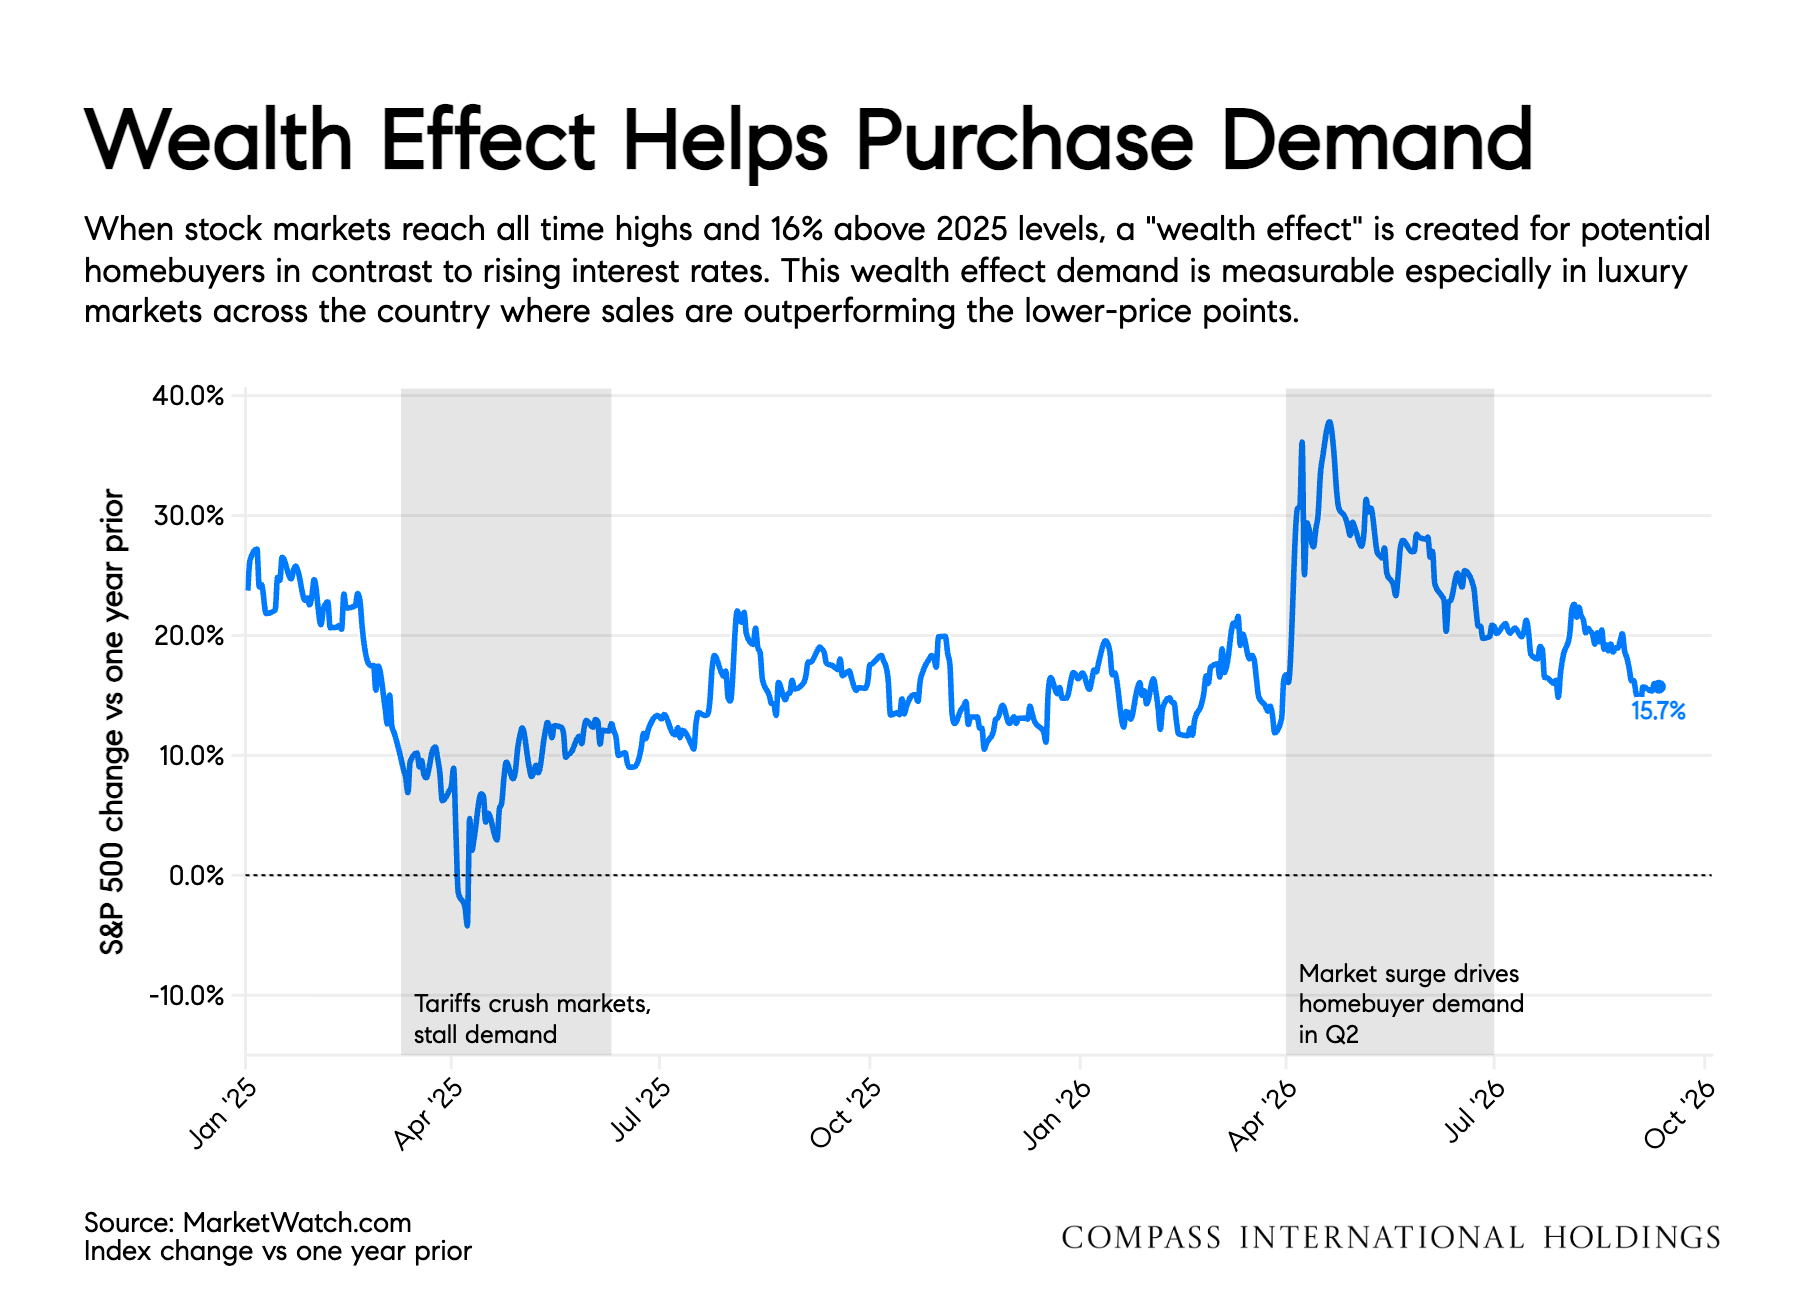
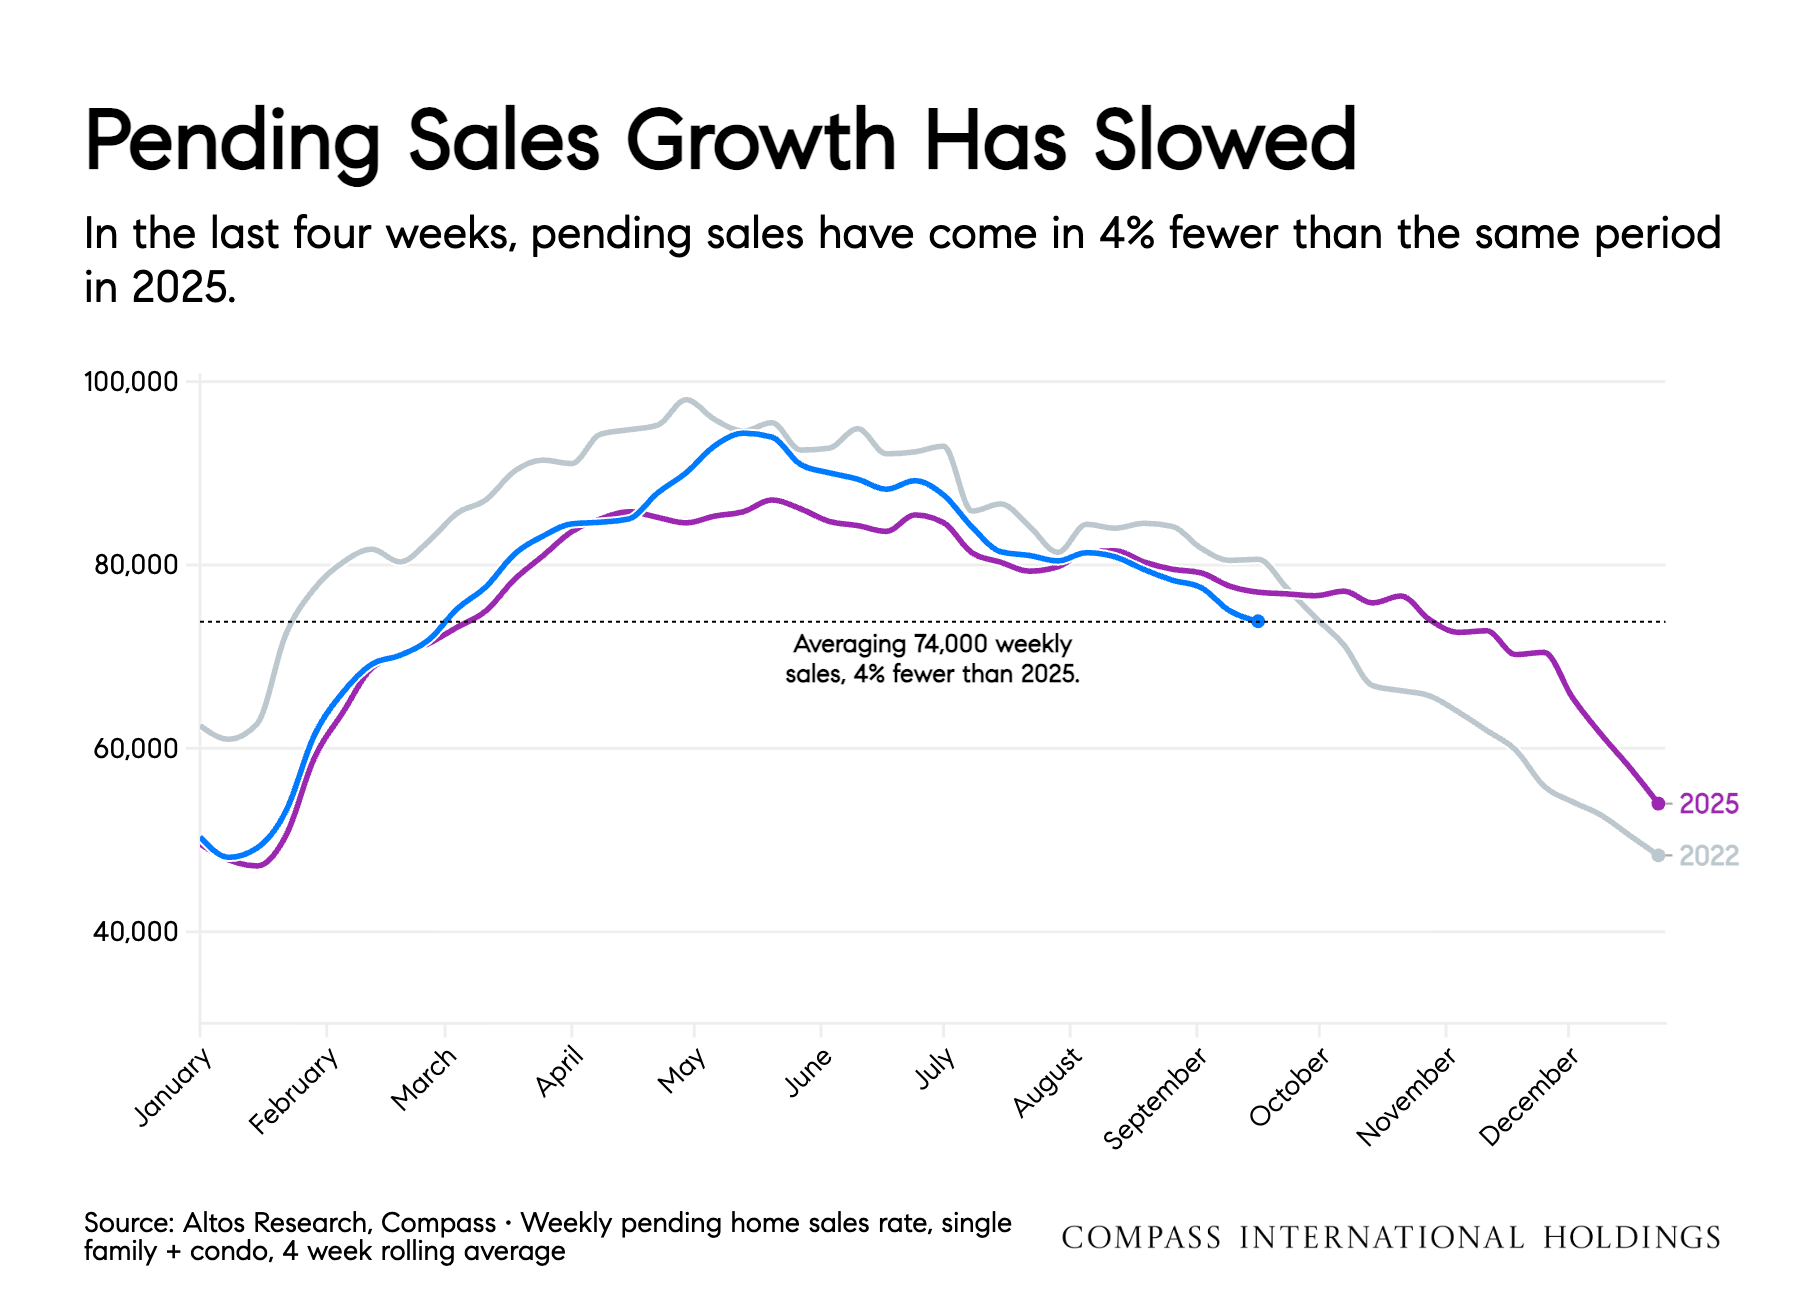
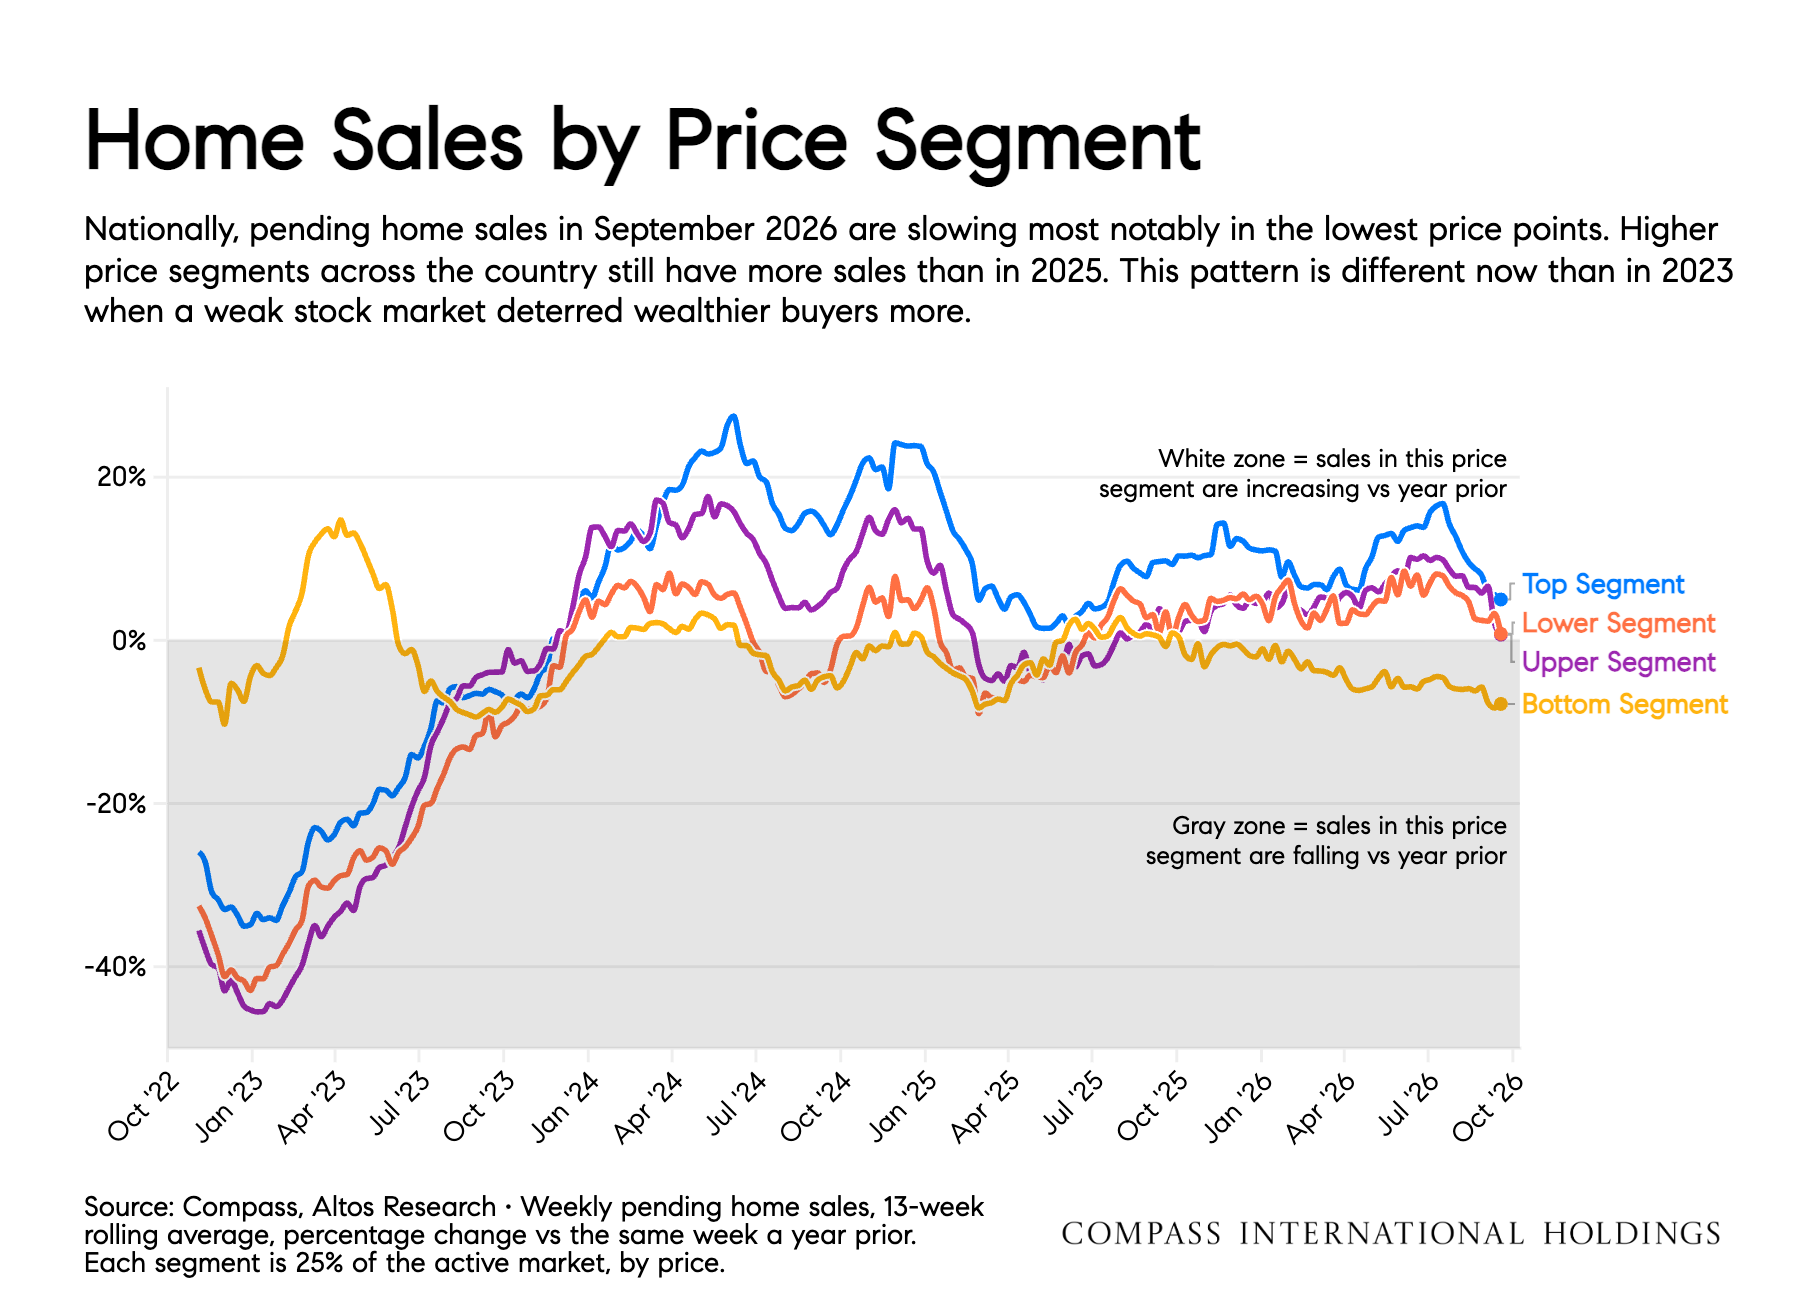
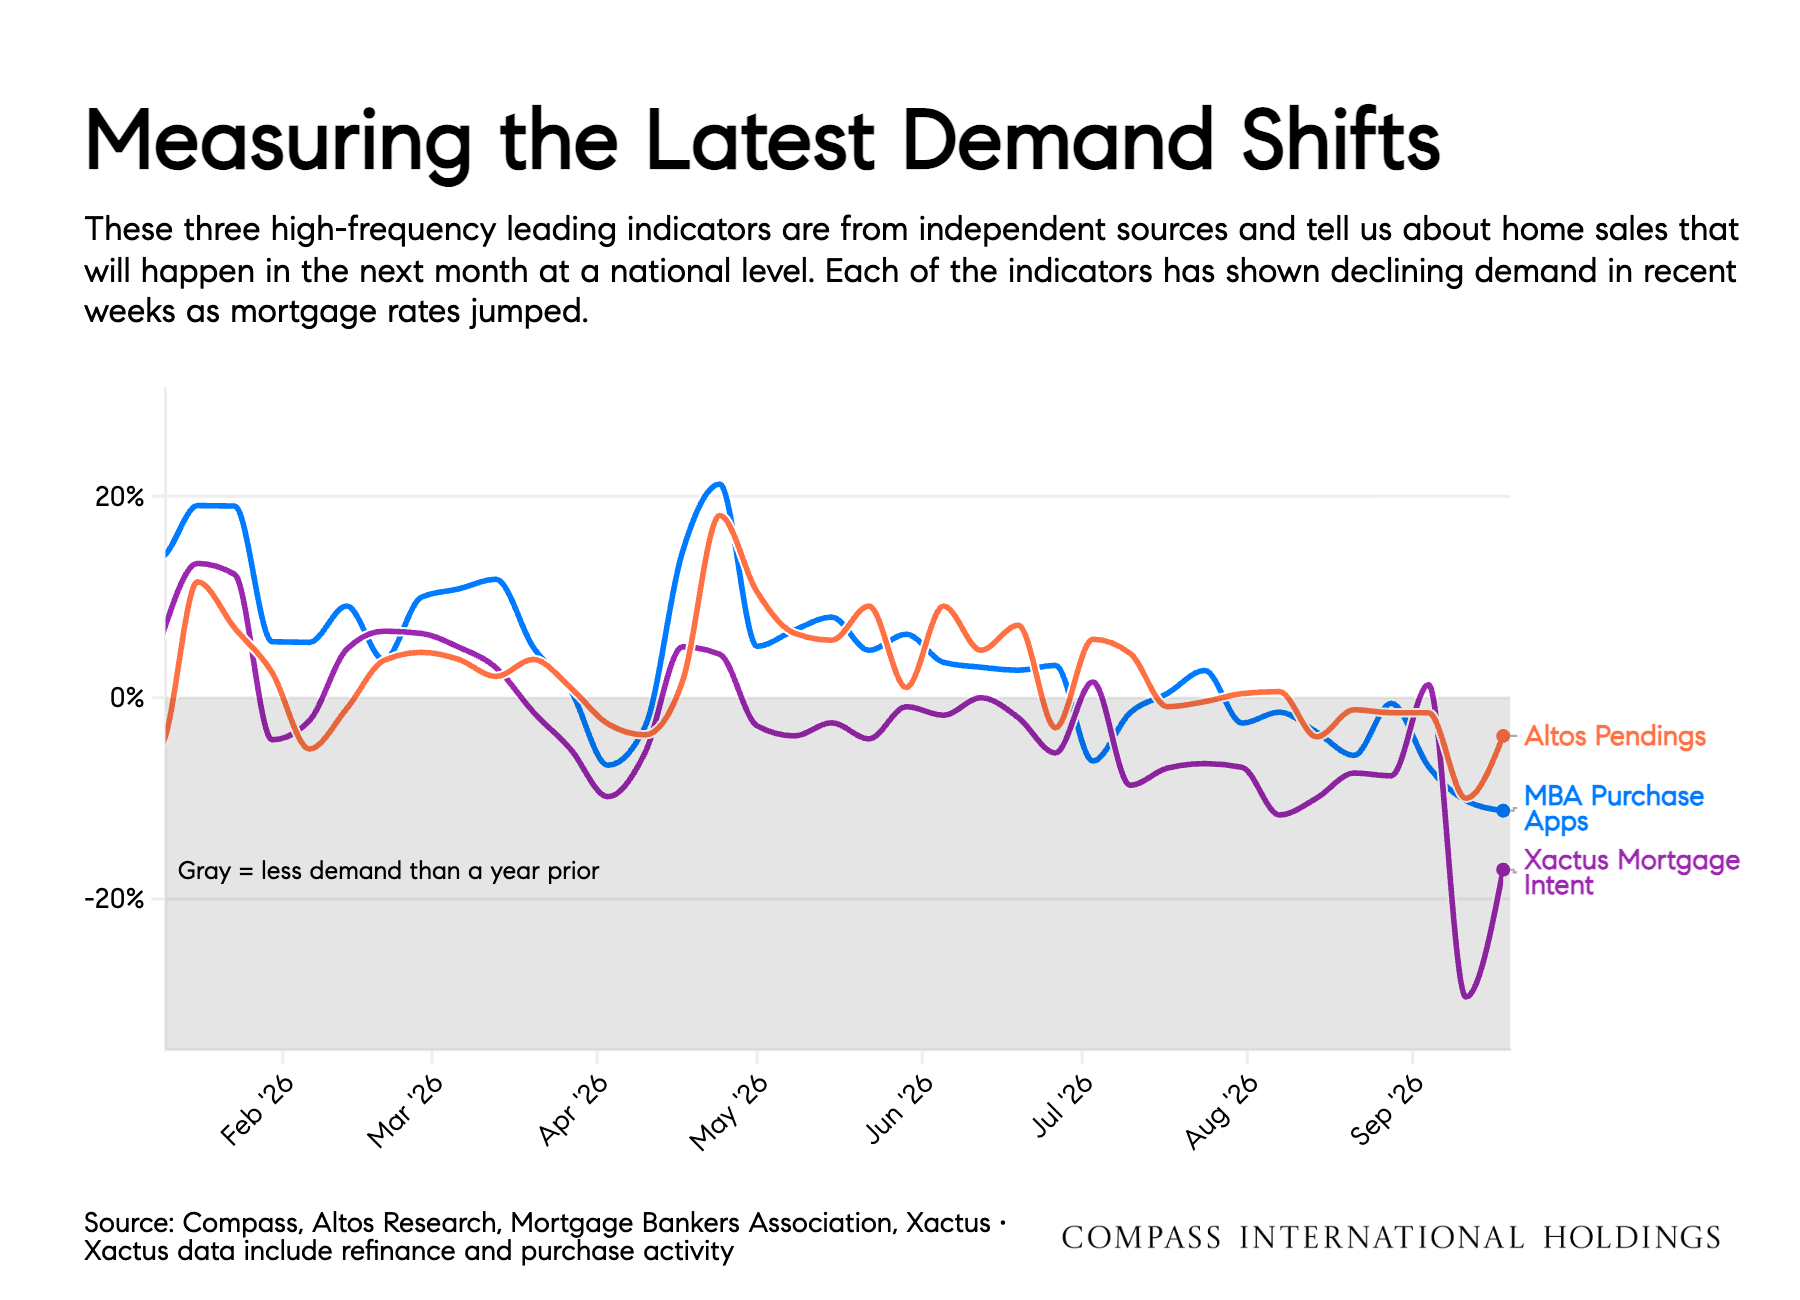
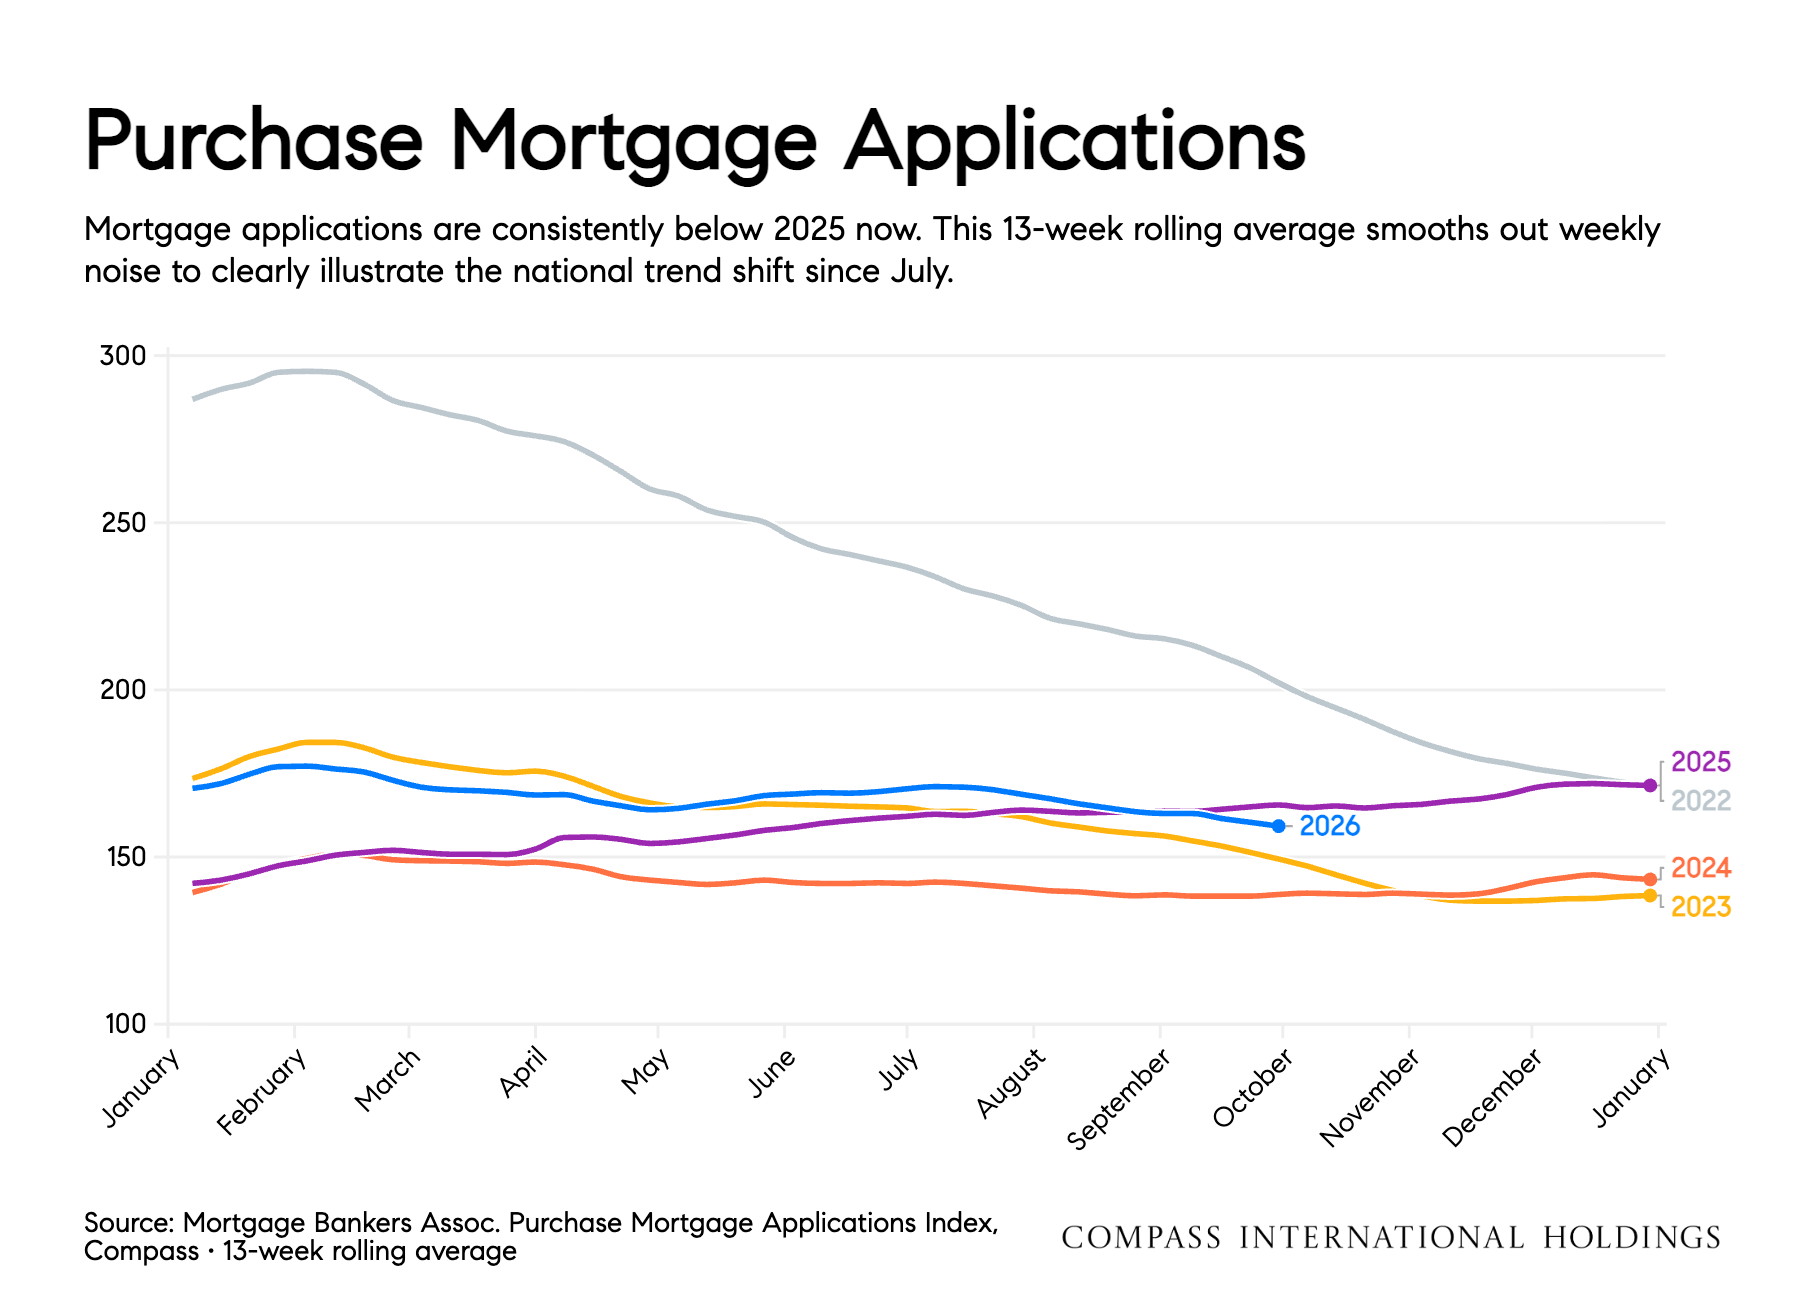
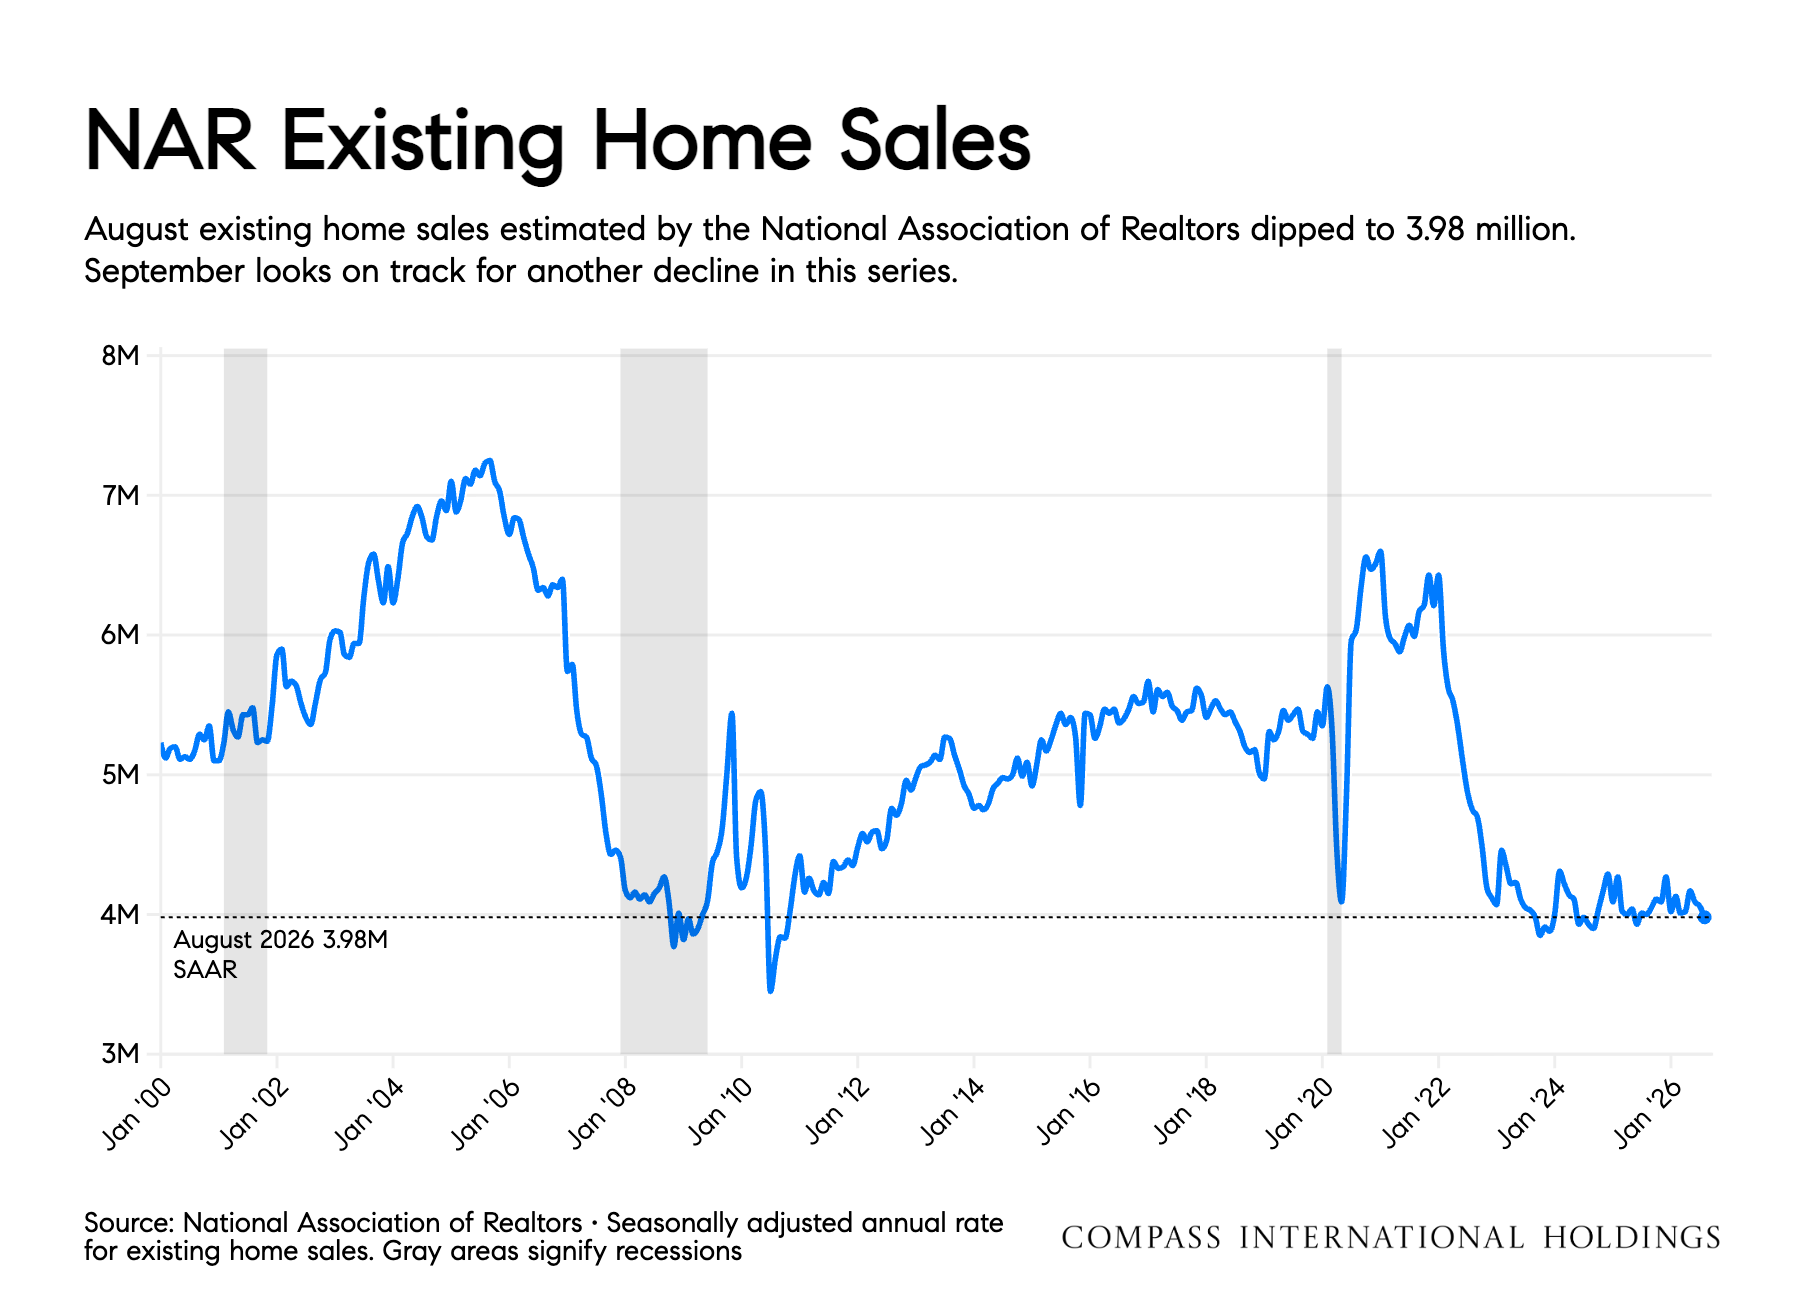
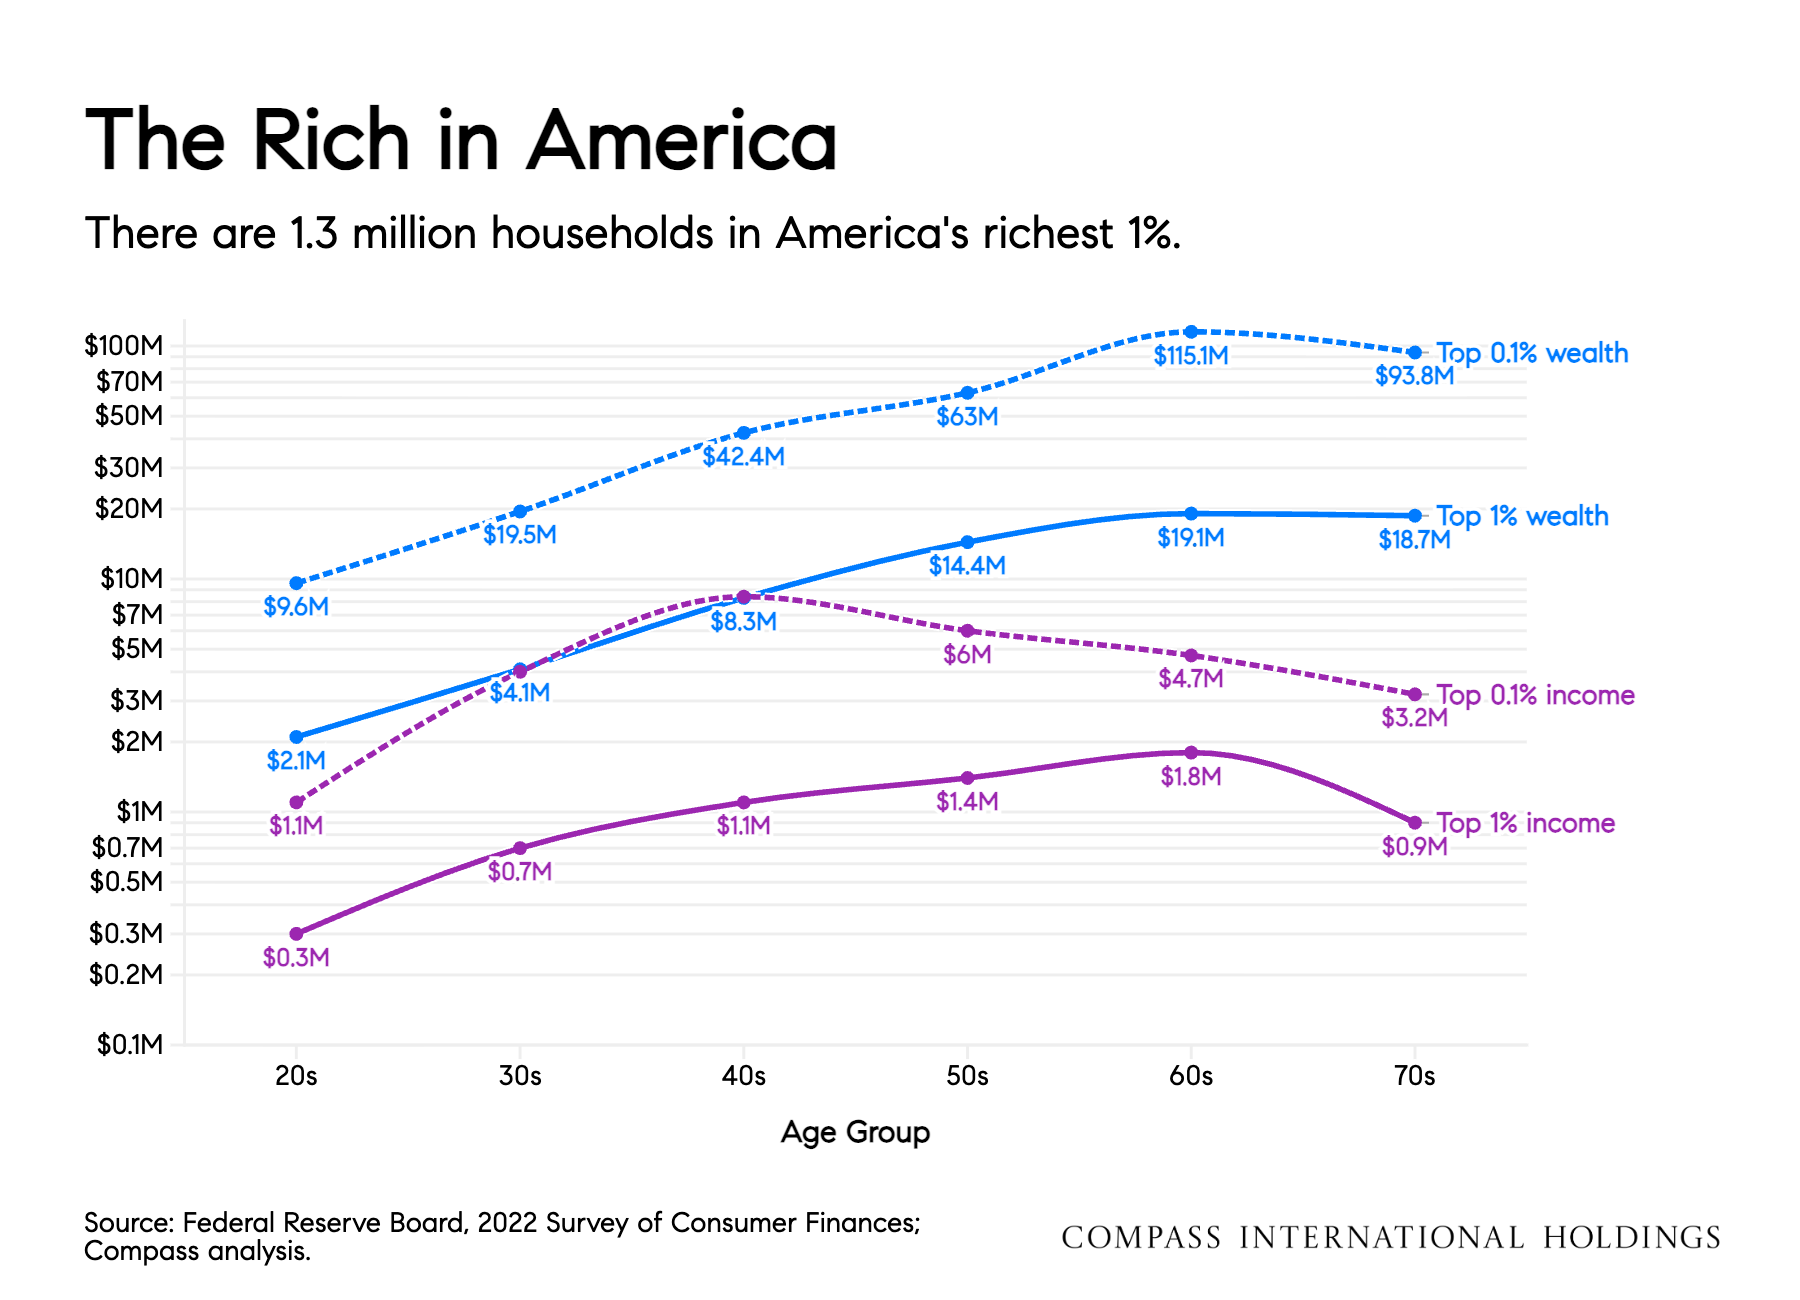
Housing demand is feeling it. Overall, pending sales over the last four weeks are running 4% below last year. Every high-frequency demand indicator we track (our own pending sales, MBA purchase applications, and Xactus mortgage intent) turned down as rates jumped. The weakness is concentrated at the lower price points. With the S&P 500 up nearly 16% from a year ago, the wealth effect is keeping the luxury segment ahead of 2025.
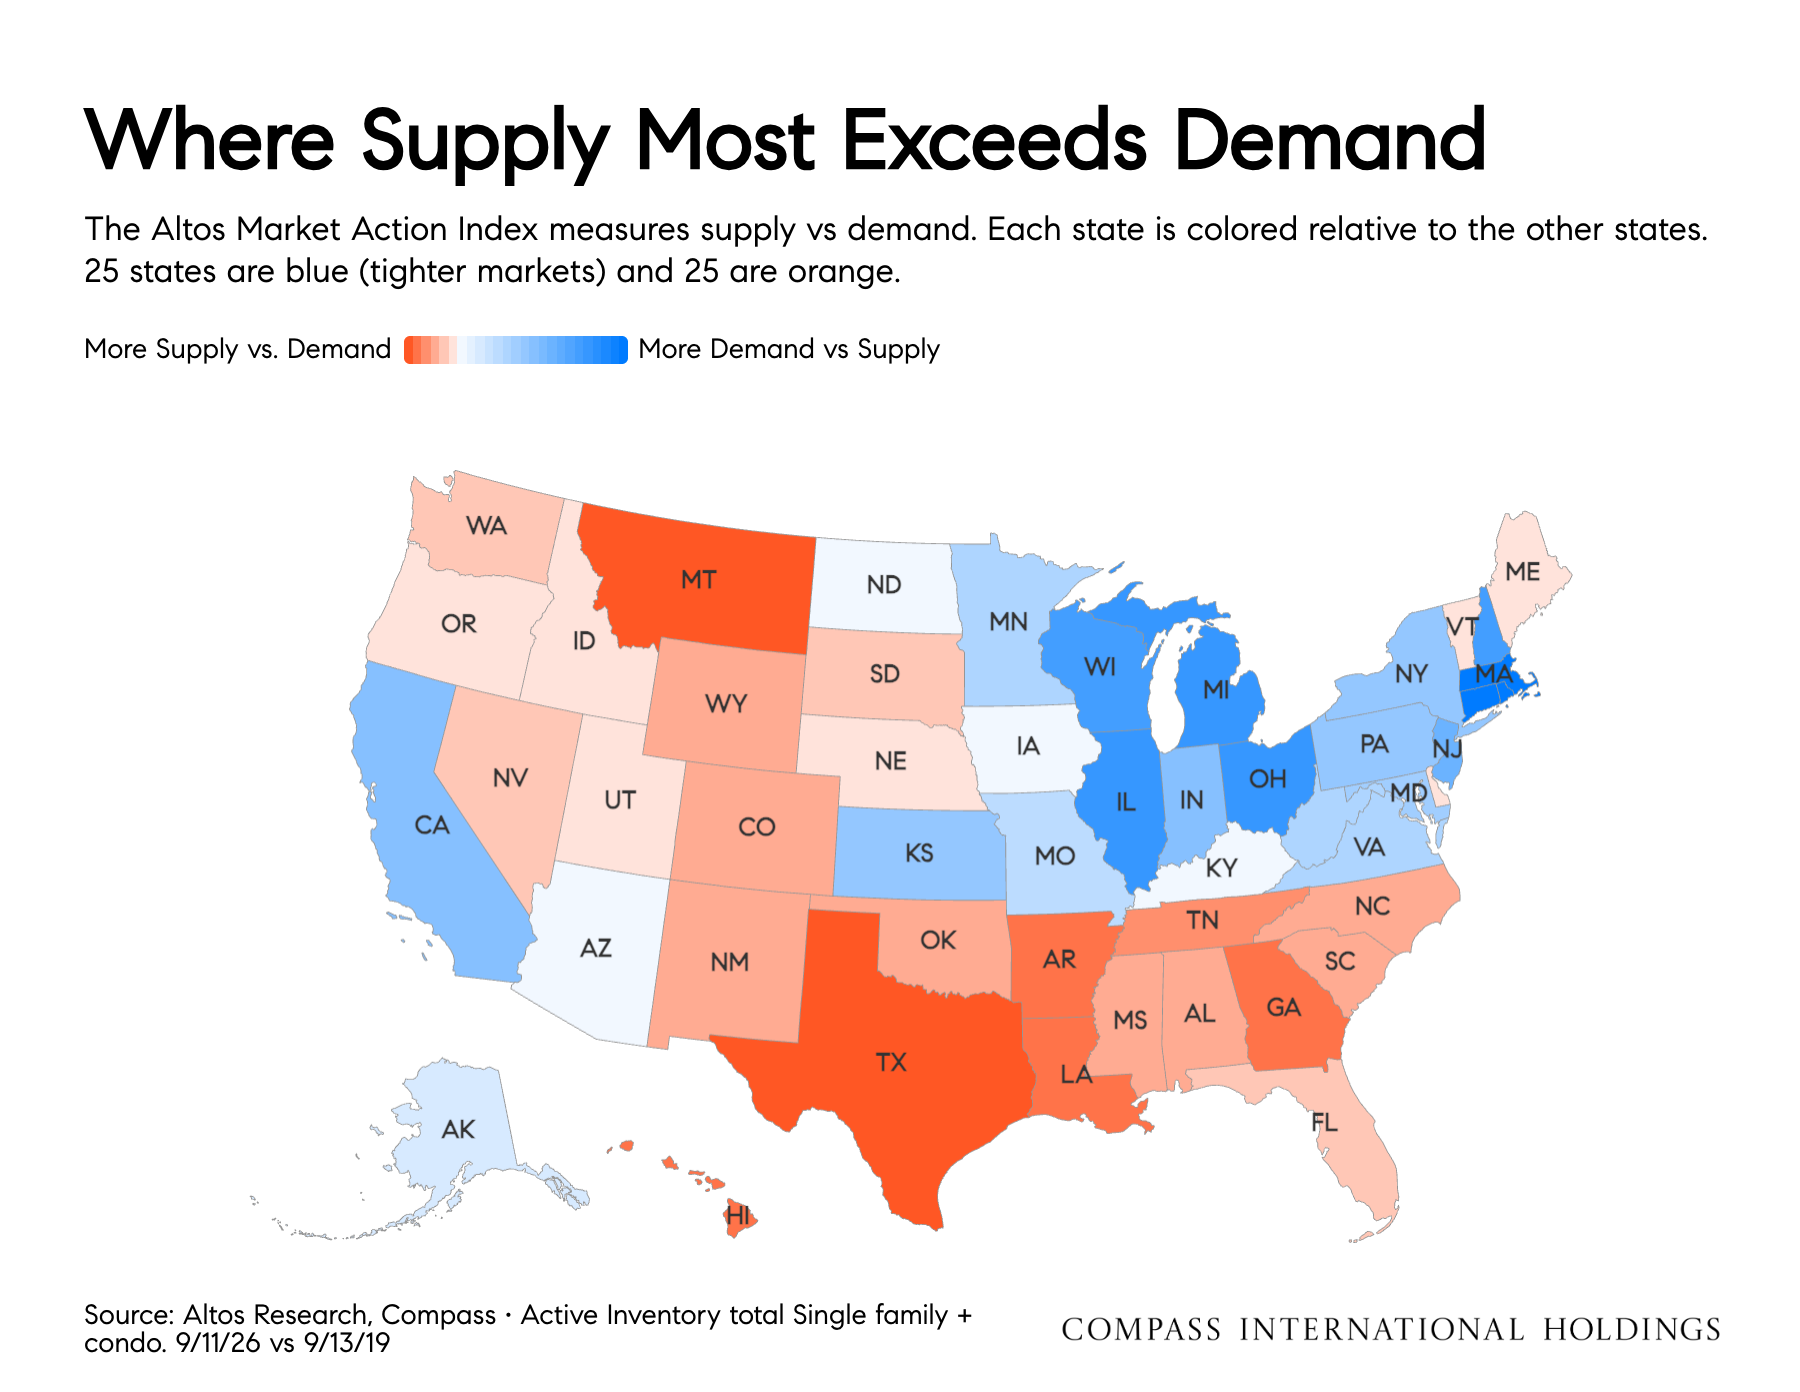
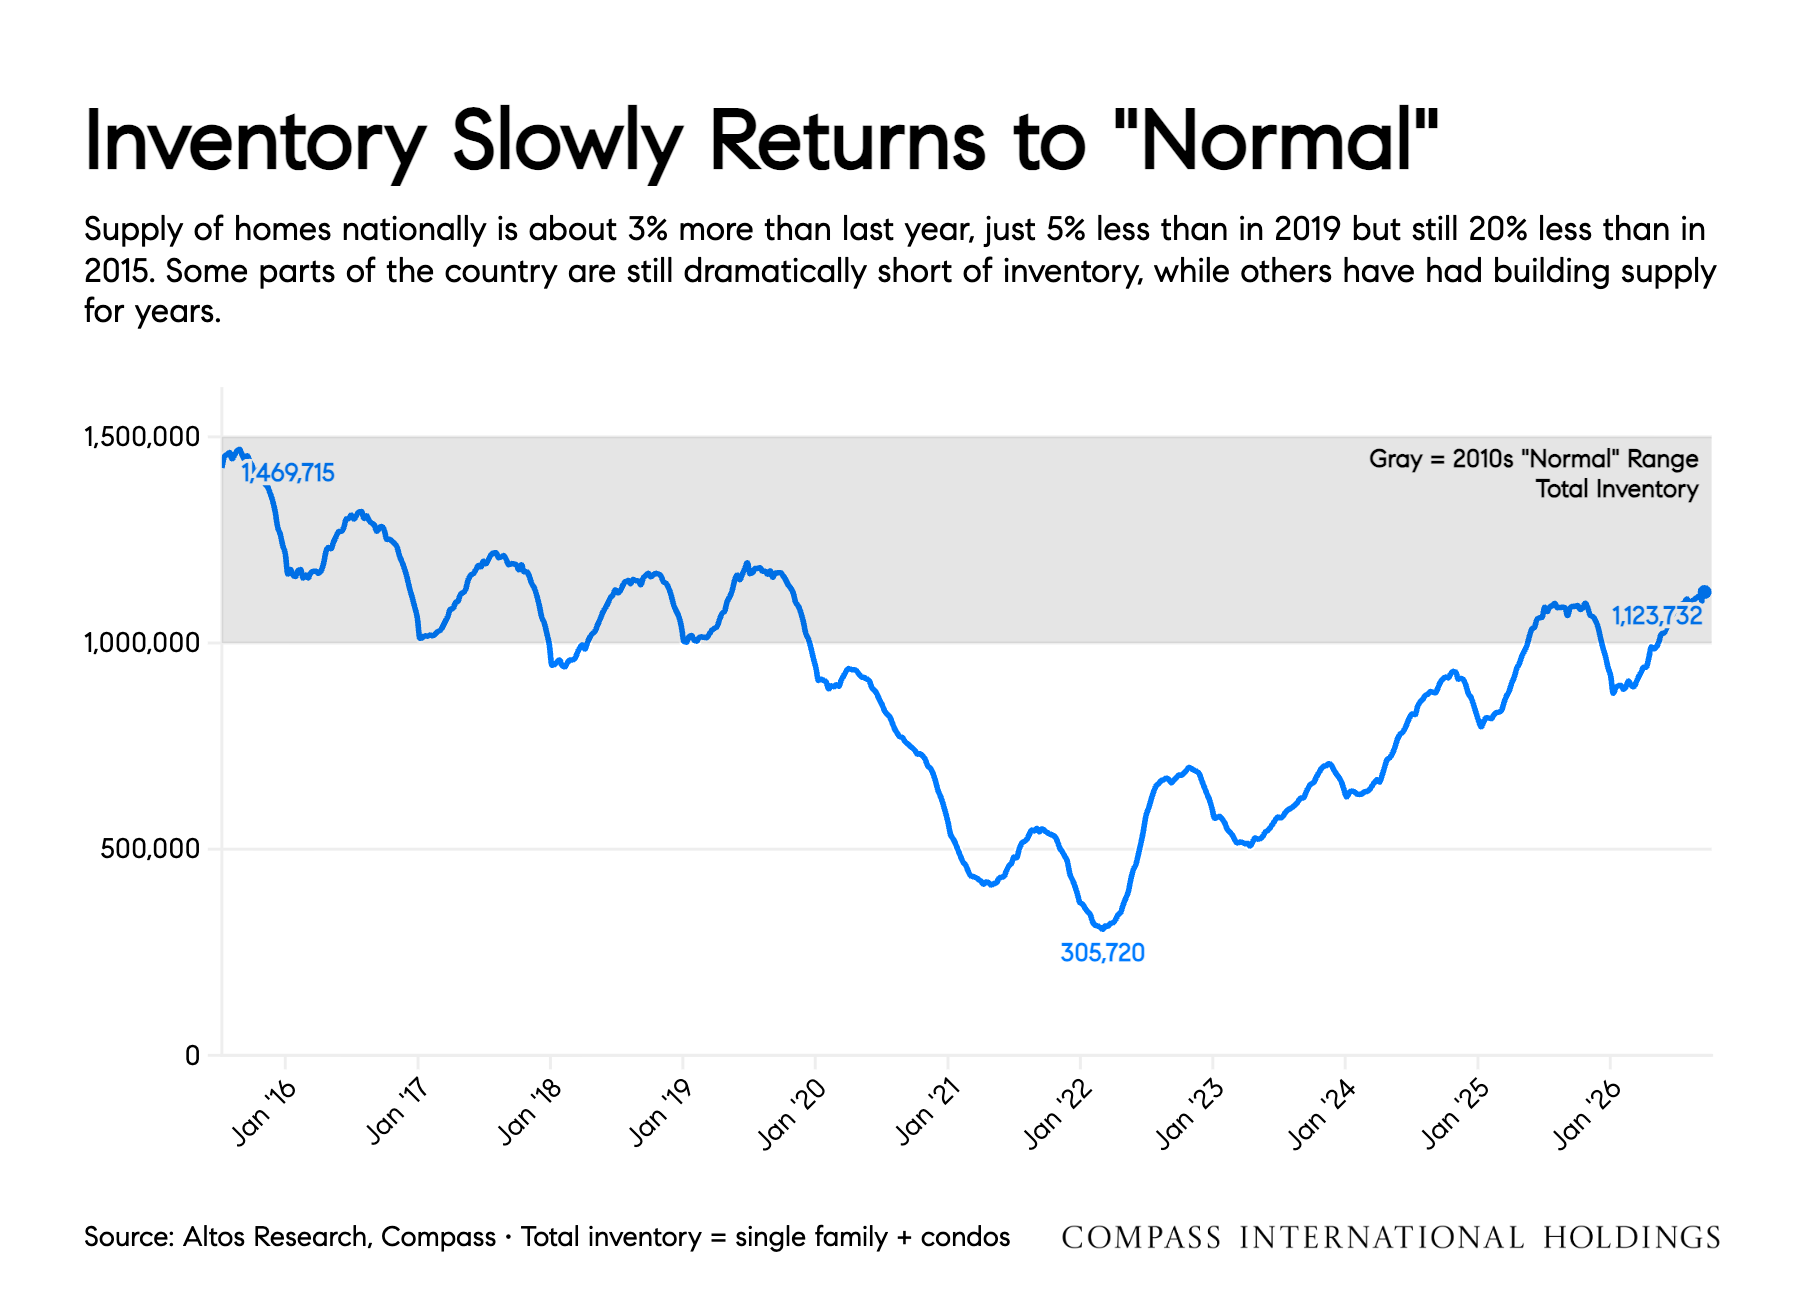
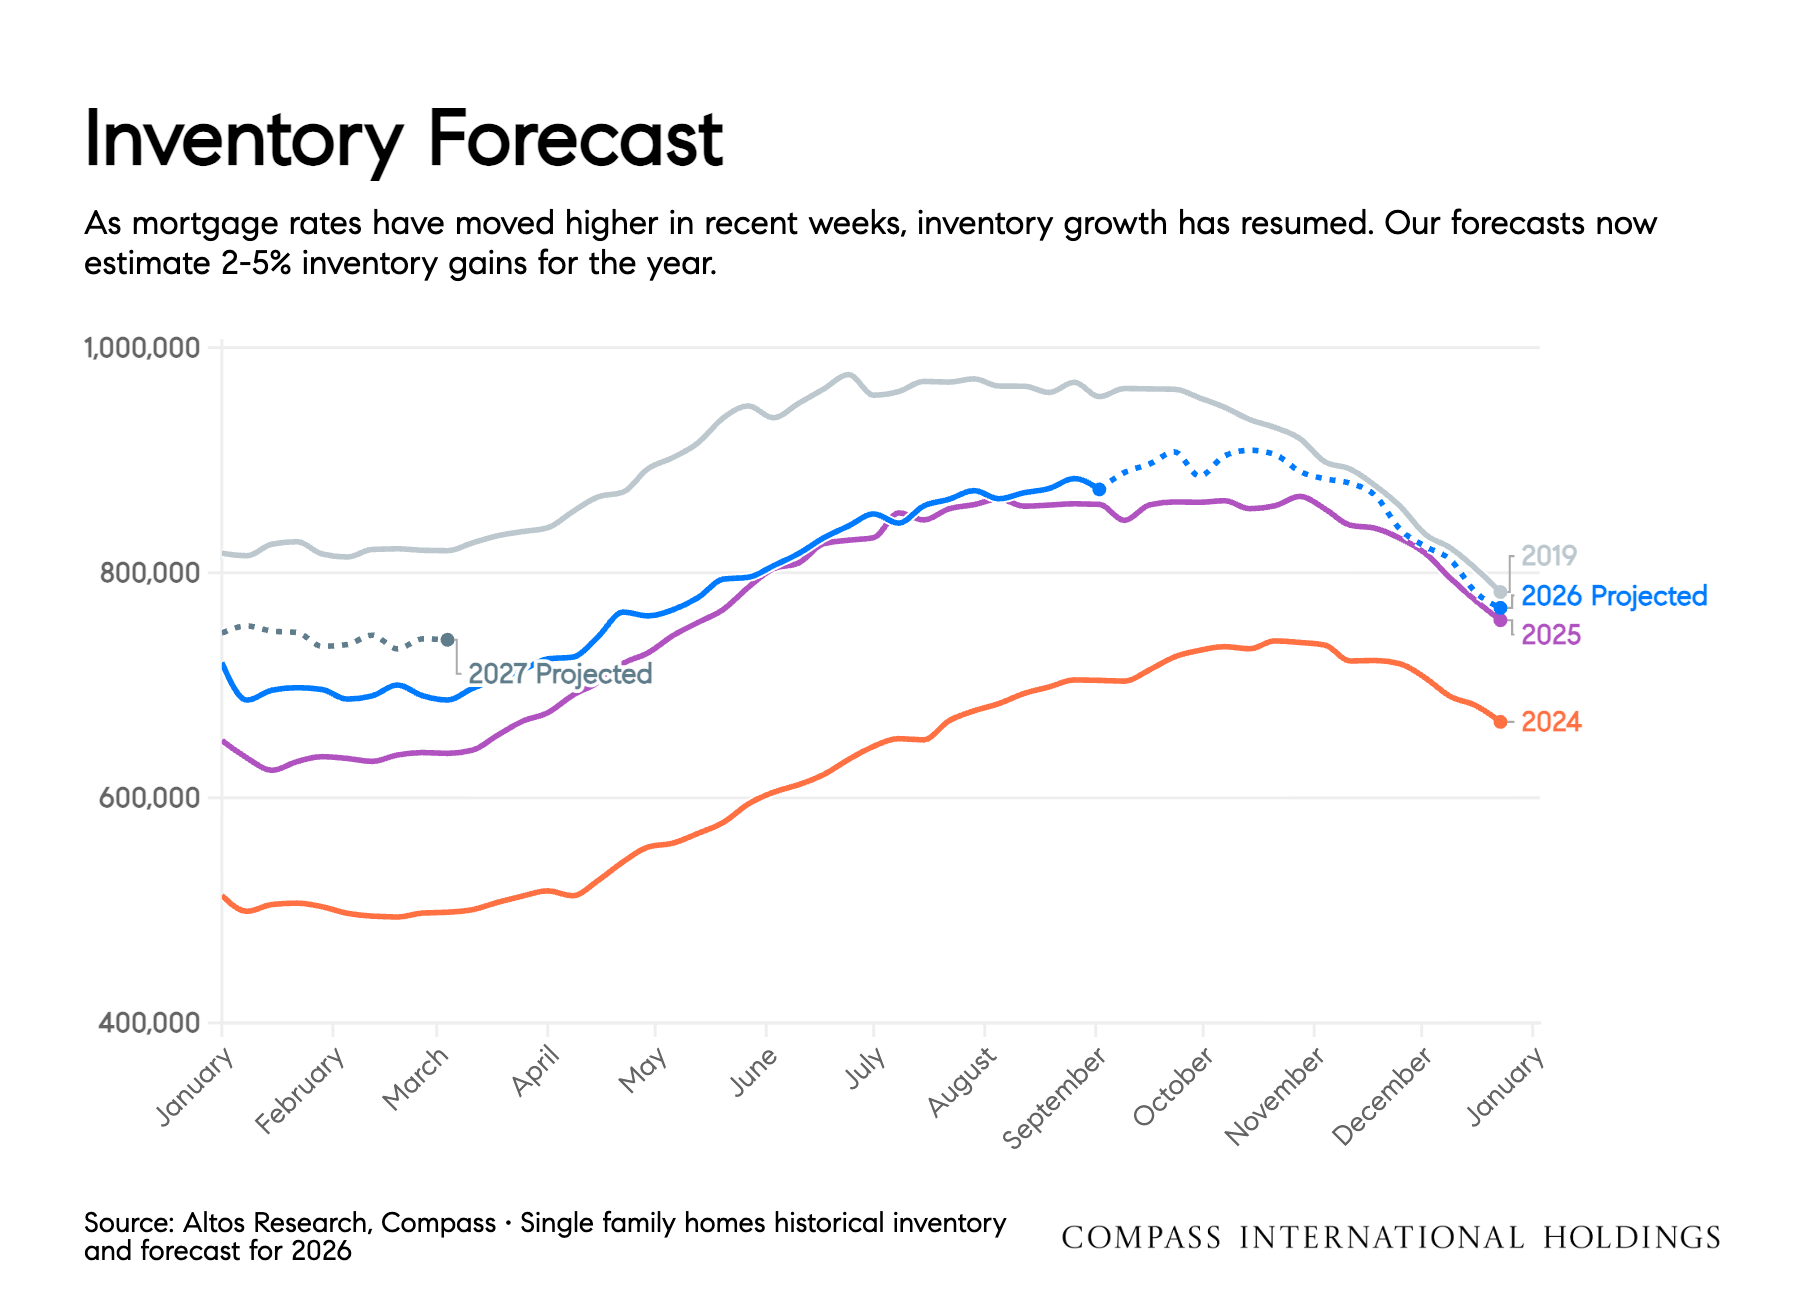
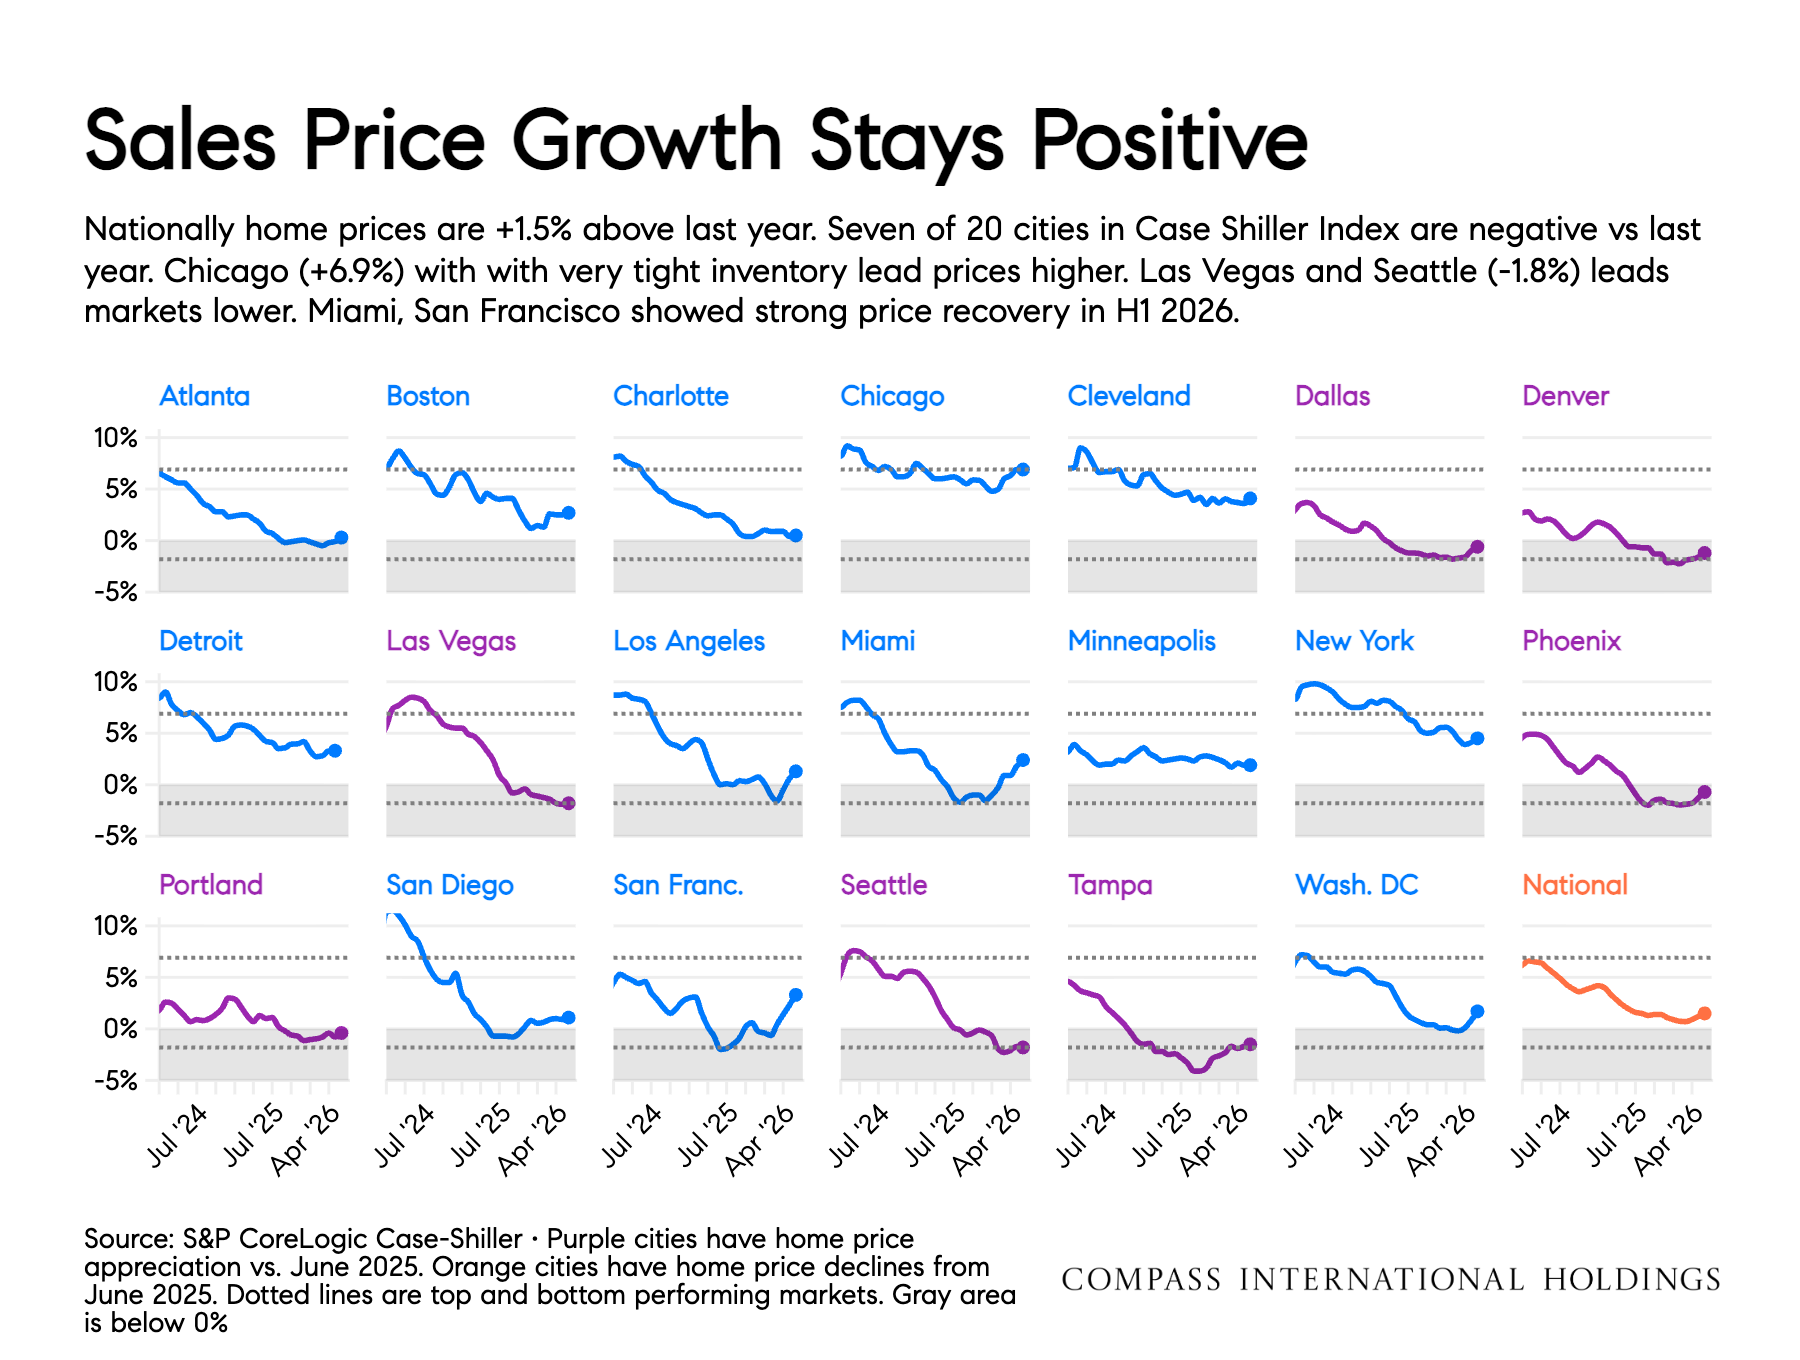
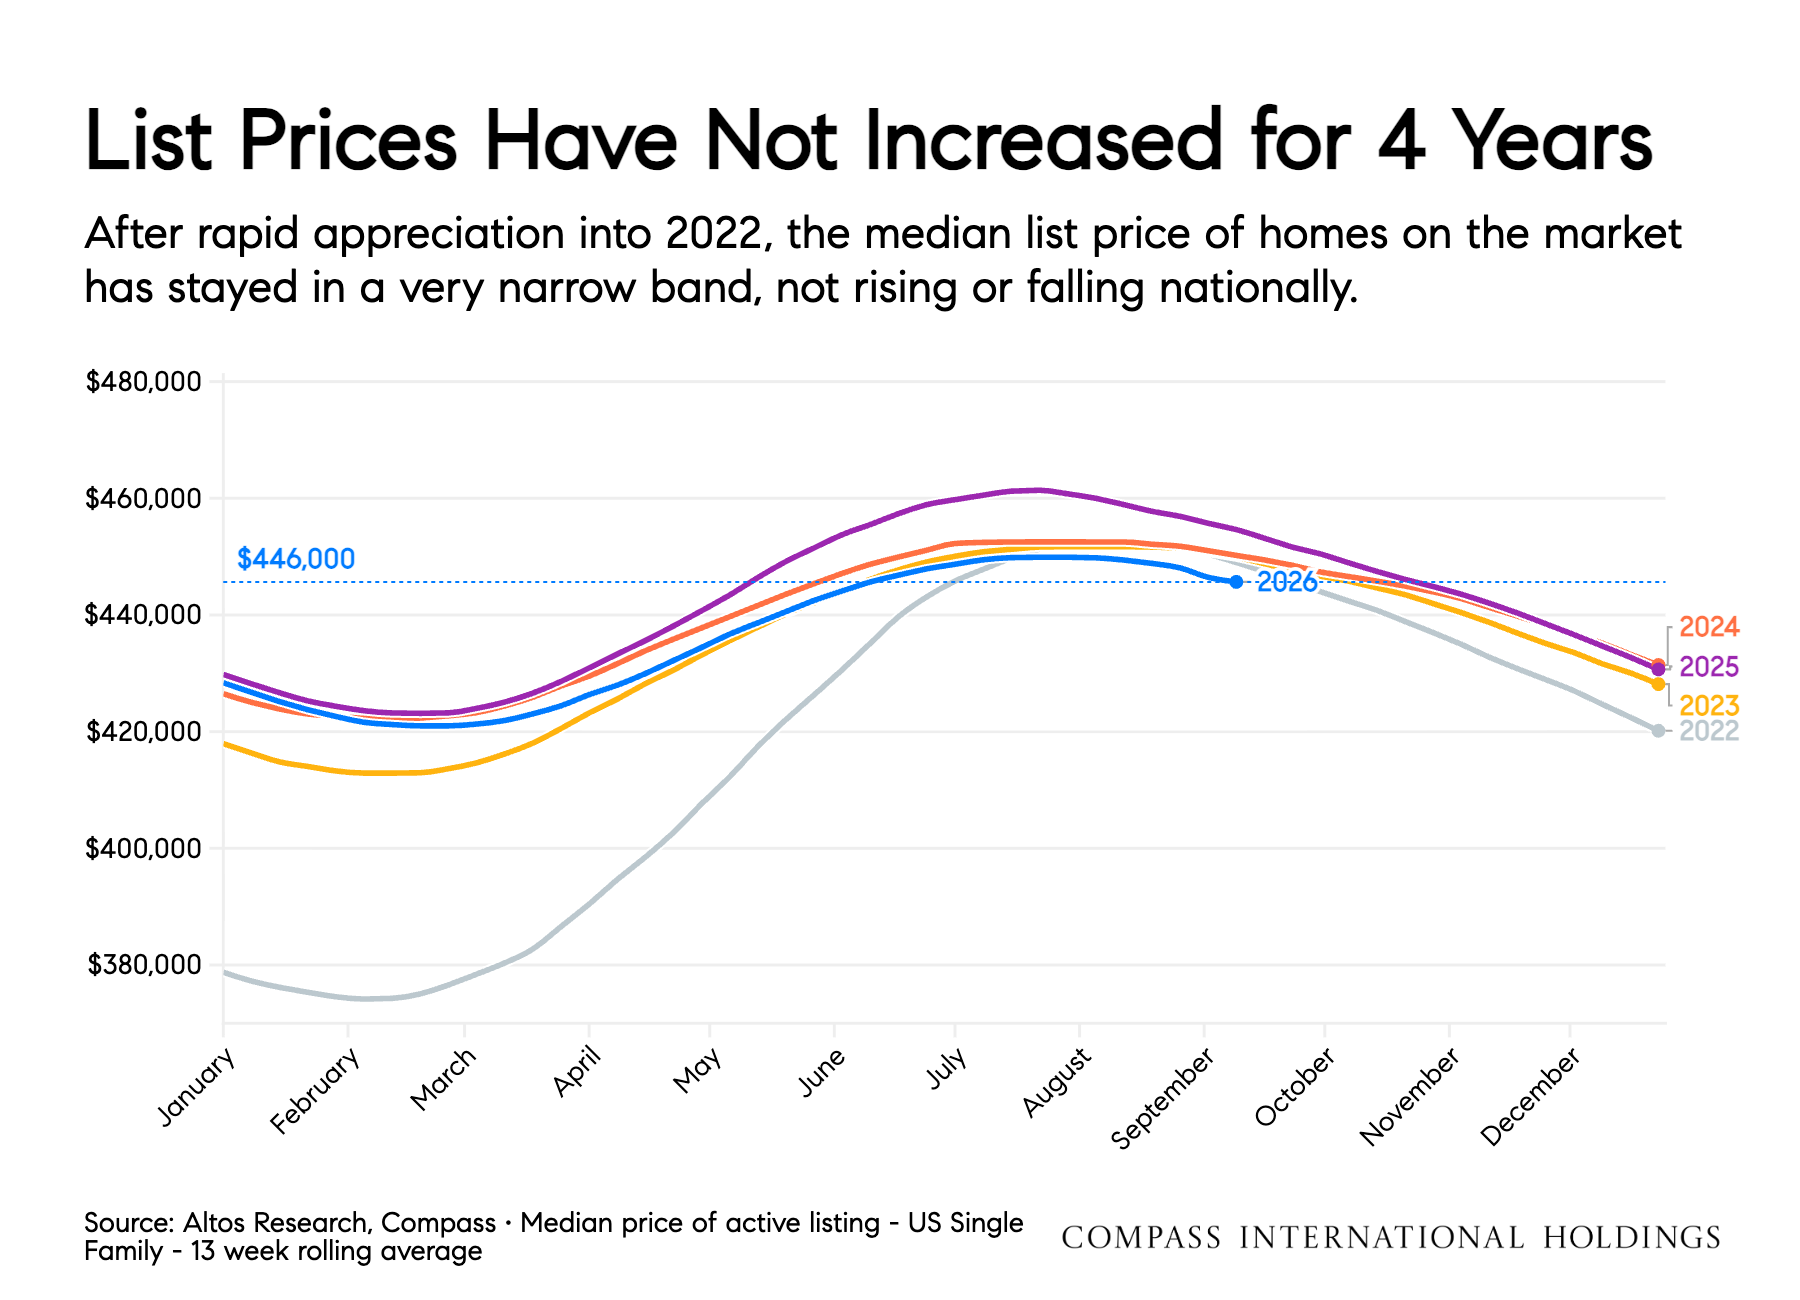
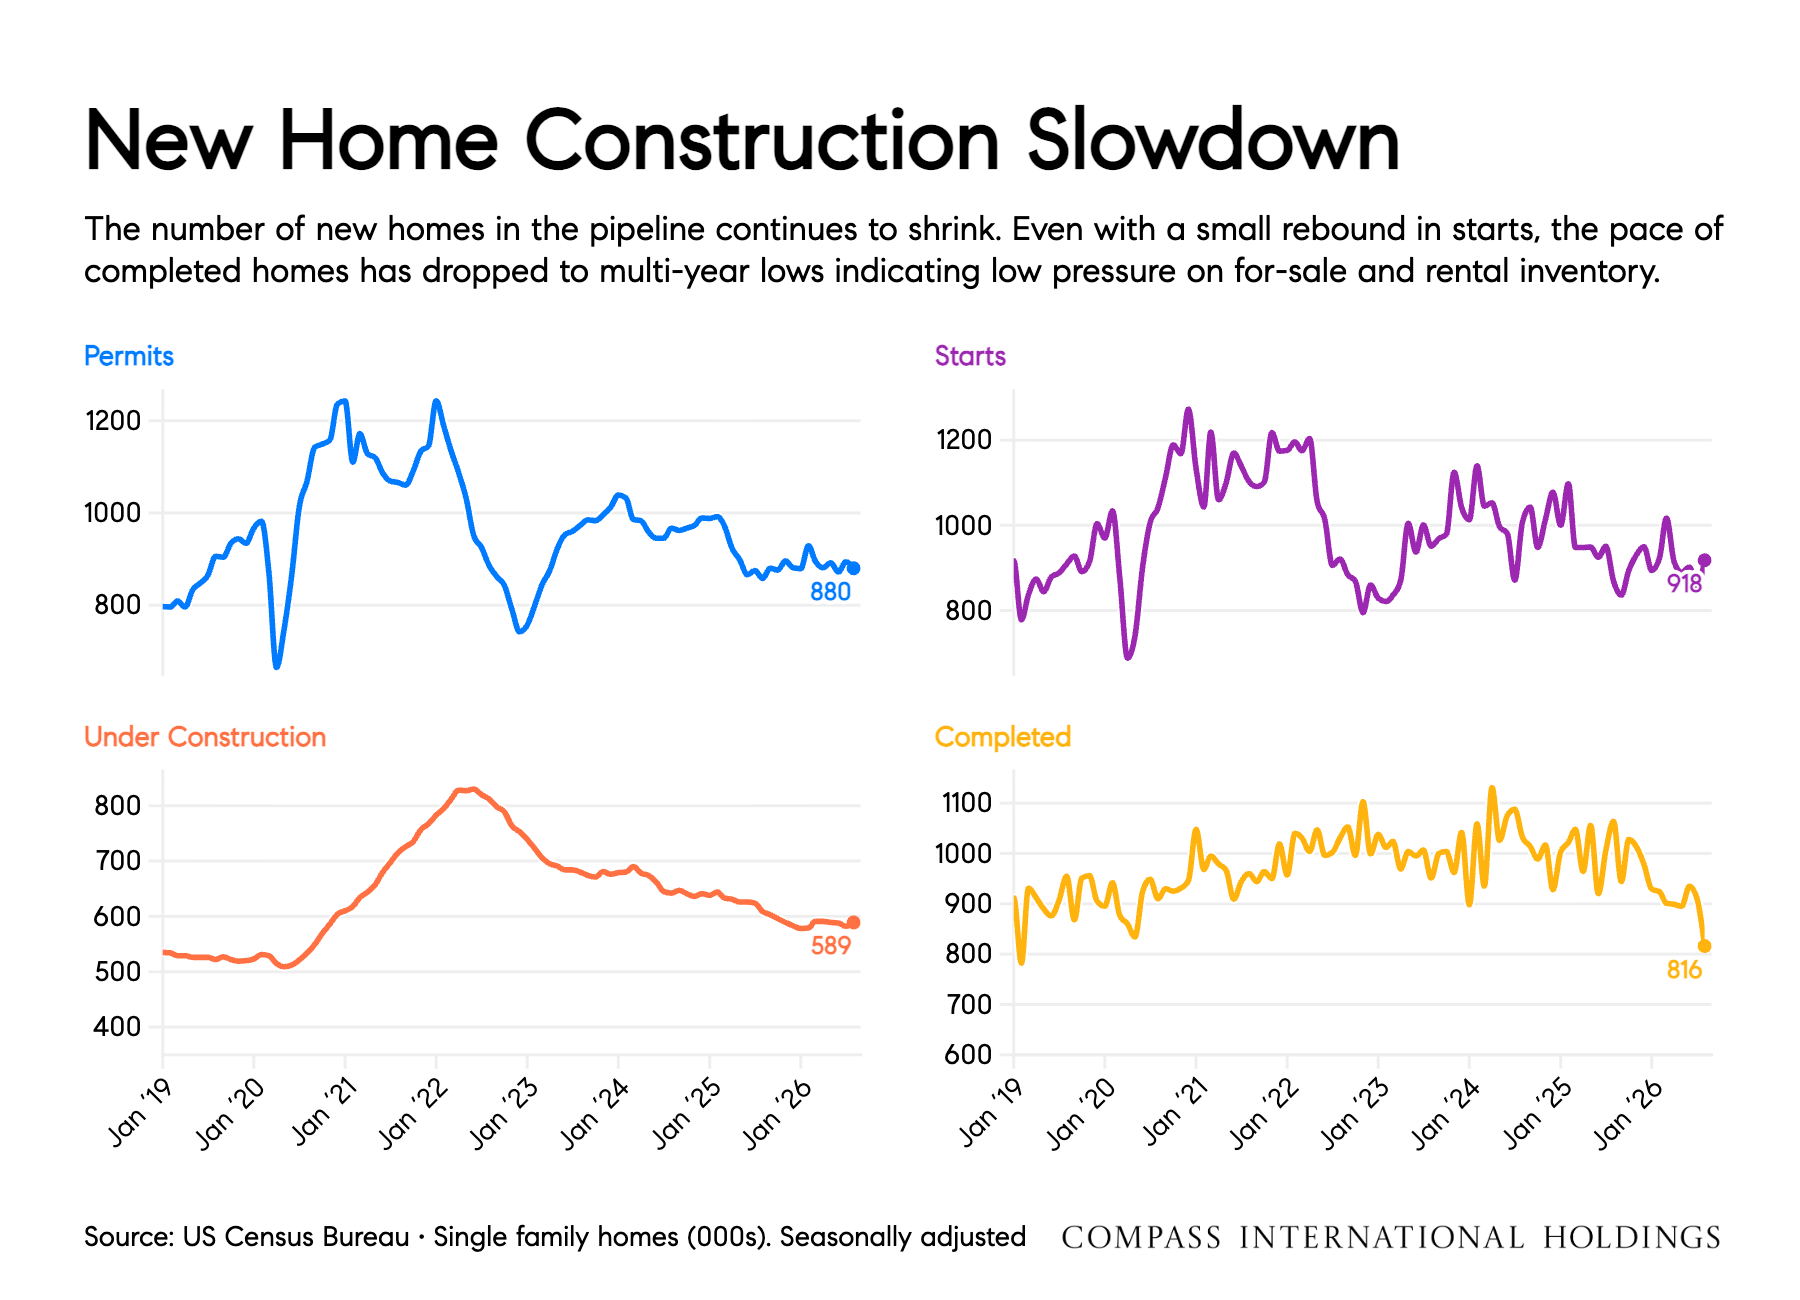
On the supply side, inventory is growing again, and we now expect 2–5% gains for the year. Nationally, supply is just 5% below 2019, though conditions vary dramatically from state to state. Prices are holding: home prices are up 1.5% year over year, and median list prices have stayed in a narrow band for four years.
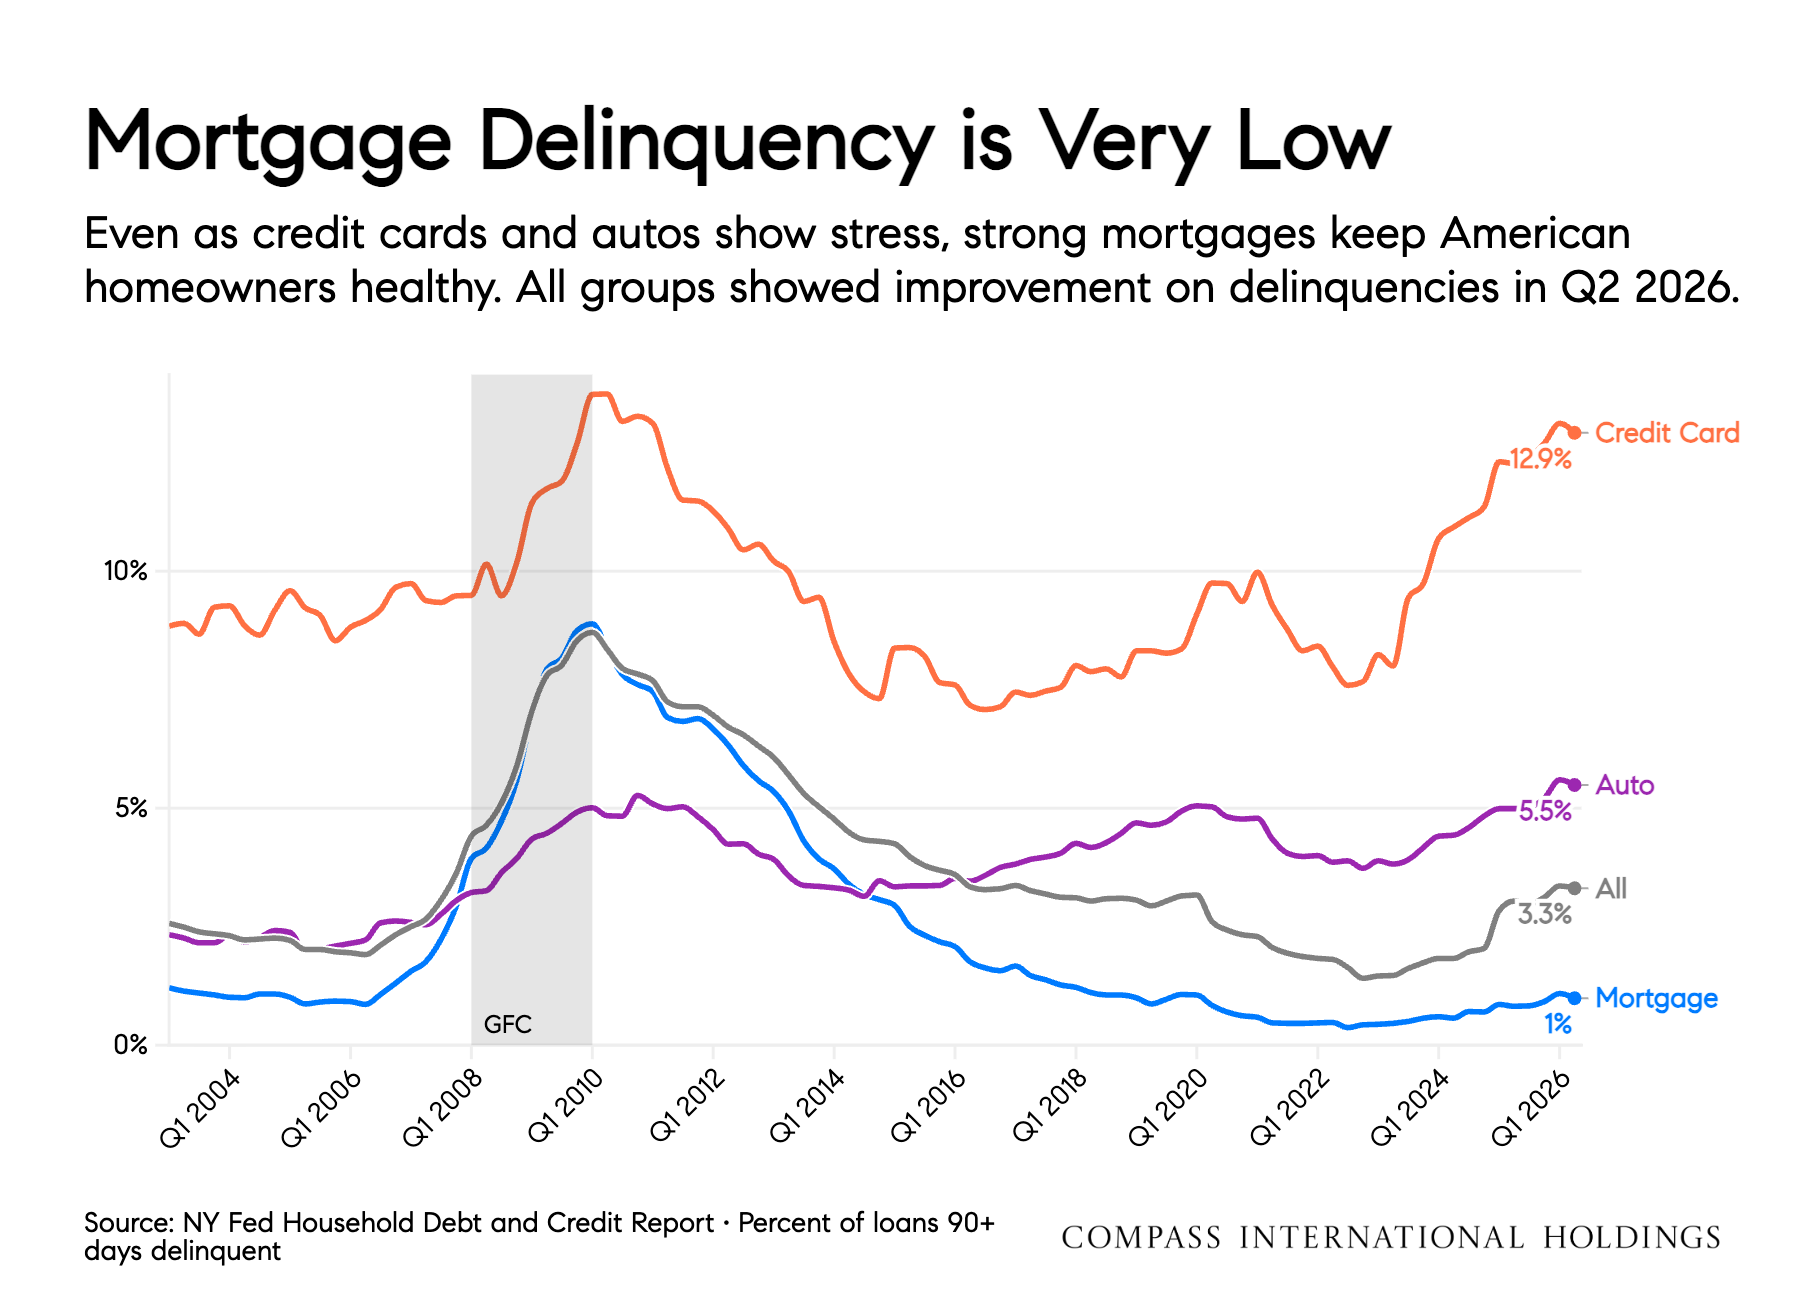
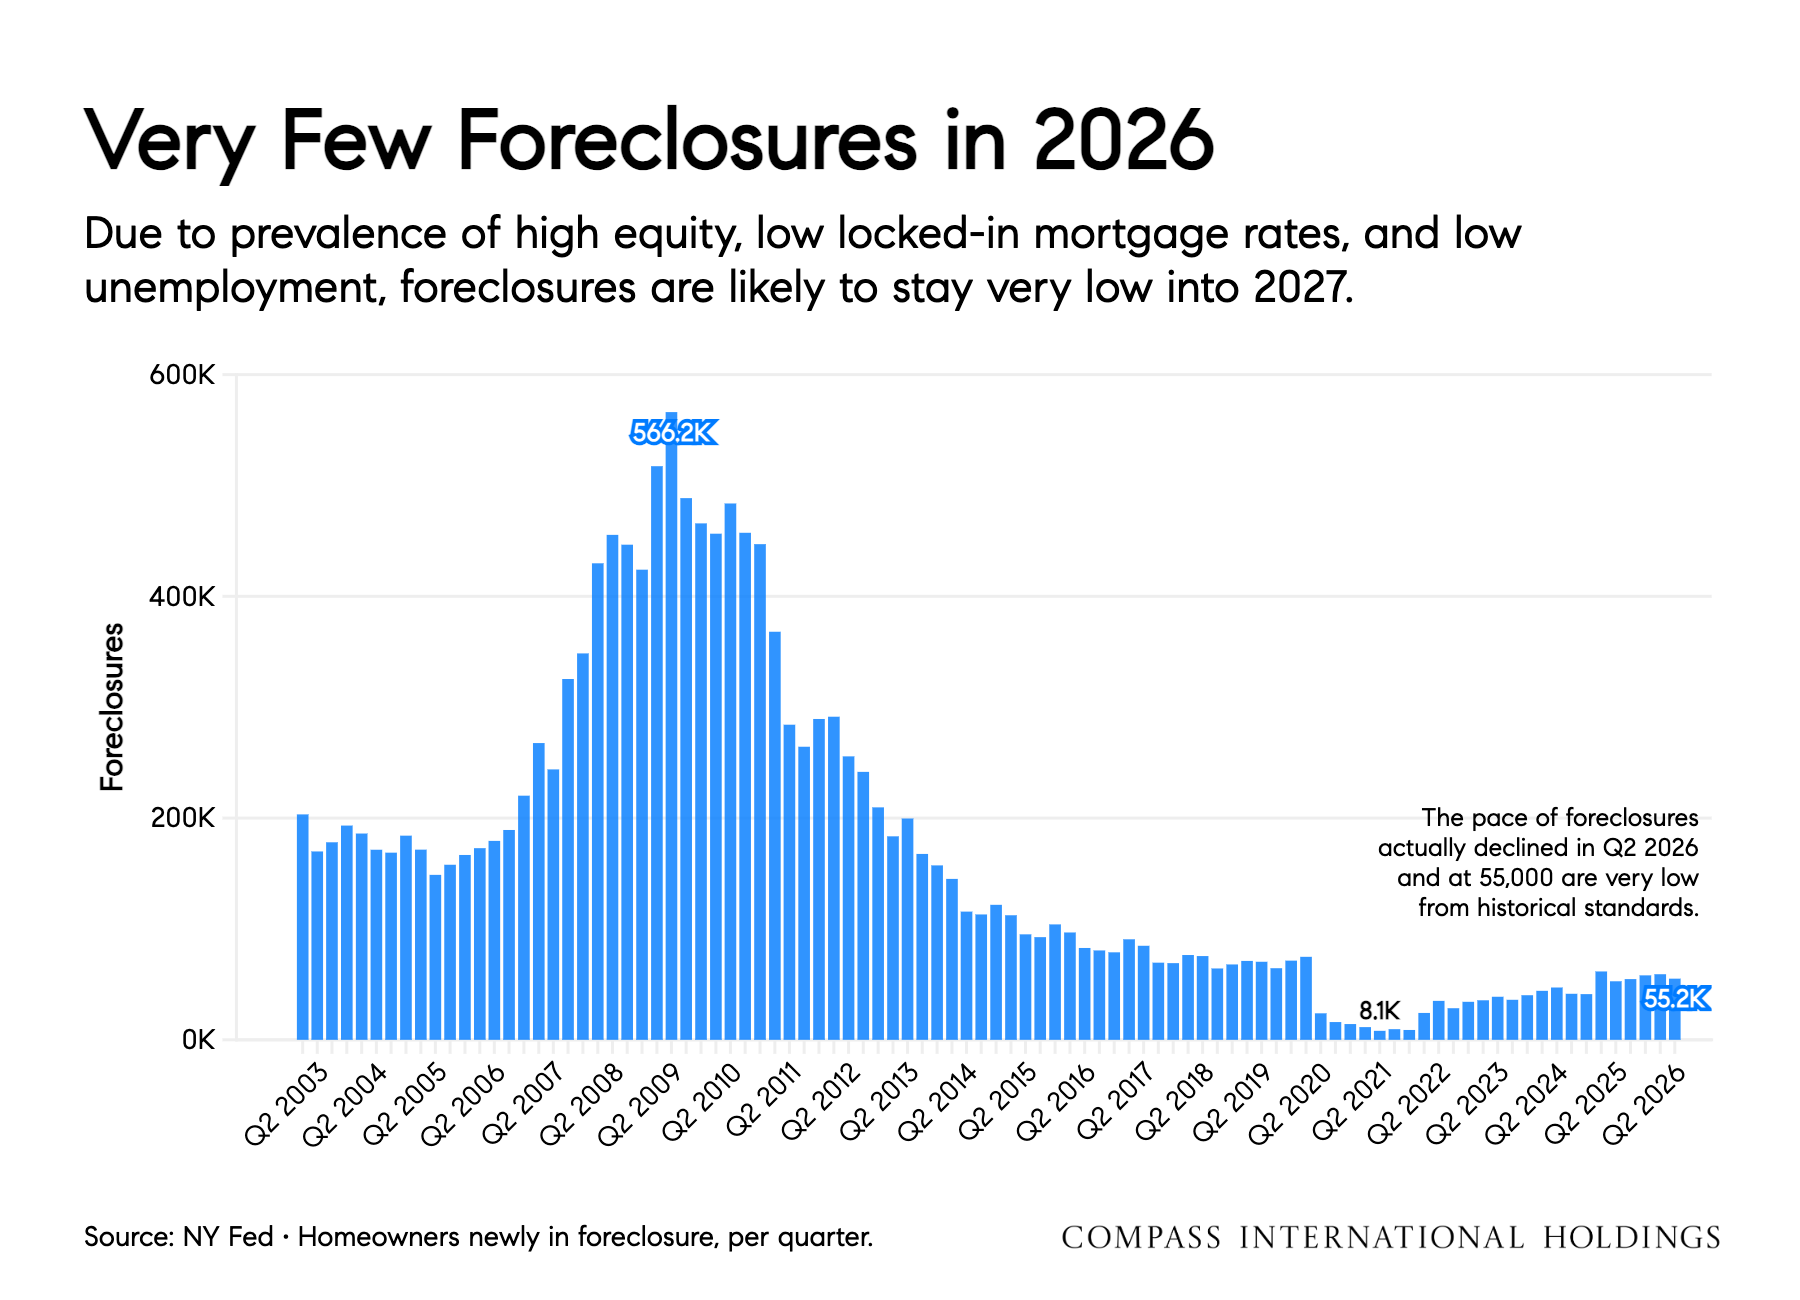
Importantly, this is not a distressed market. Mortgage delinquencies are near 1%, and foreclosures remain very low by historical standards.
The slides below walk through each of these trends in detail. As always, reach out with questions.
Mike Simonsen
Chief Economist | Compass International Holdings